The factory fire is over. The damaged machine has been surveyed. The material-damage claim may even be admitted. But the business is still running at half capacity, customers are waiting, salaries and rent continue, and the loss-of-profit settlement comes back far lower than the number in the company’s books.
That is where business-interruption claims become difficult. The dispute is rarely about whether the business lost money in a general sense. It is about whether the policy covers that particular loss, for what period, on what turnover baseline, at what policy-defined gross-profit rate, after which savings, increased costs, trends, excess and underinsurance adjustments.
A business can genuinely be under severe financial pressure after a fire and still have a weak BI claim if the policy trigger is not met or the calculation is unsupported. The reverse is also true: a surveyor can produce a neat spreadsheet that is wrong because it uses the wrong department, wrong standard turnover, wrong indemnity period or ignores a valid trend/output clause.
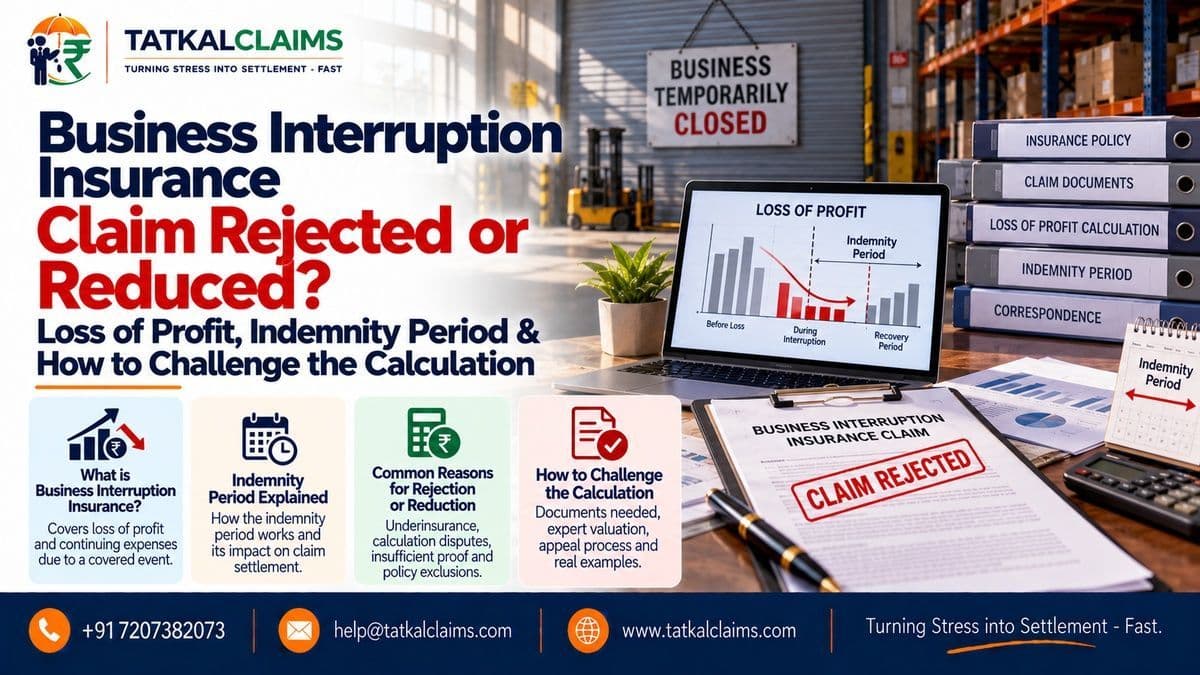
What Business Interruption / Loss of Profit Insurance Actually Covers
In Indian commercial insurance, business interruption is commonly called Loss of Profit (LOP), Fire Loss of Profit (FLOP) or Consequential Loss. It may appear as a separate consequential-loss policy or as Section II of a package/Industrial All Risk policy.
The core idea is not to pay for the damaged building or machine again. Material-damage cover deals with the property. BI cover deals with the financial effect on the business when insured physical damage interrupts or interferes with operations.
Current commercial policy wordings illustrate the structure clearly: the BI section responds when the business is interrupted or interfered with because of loss, destruction or damage that is indemnifiable under the material-damage section, and the insured loss is then calculated through reduction in turnover and increased cost of working.
Why the Material-Damage Claim Matters So Much
The first BI question is usually not “How much profit did we lose?” It is “What insured physical damage caused this interruption, and is that damage indemnifiable under the underlying section or policy?”
The Delhi High Court in Nagarjuna Agrichem described loss-of-profit cover as sitting on top of the material-damage policy rather than standing independently. Current package/IAR wordings follow the same architecture by tying BI liability to damage indemnifiable under the material-damage section.
That does not mean an admitted material-damage claim automatically establishes the BI amount. It only clears the first gate. The policyholder still has to establish causation, the affected period and the financial quantum.
Conversely, if a material-damage repudiation is later overturned, the original reason for refusing the BI trigger may disappear—but the insurer can still dispute the BI calculation on other policy grounds.
If the insurer has not shared the property-damage or BI survey report and working papers, start with our claim-file and survey-report evidence guide so you can see the calculation being used against the claim.
Maximum Indemnity Period Is Not the Same as the Actual Claim Period
This is one of the most common misunderstandings. A schedule may show a maximum indemnity period of 6, 12, 18 or 24 months. That is a ceiling, not an automatic payout period.
Current BI wording defines the indemnity period as the period beginning with the insured damage and ending no later than the selected maximum period during which the results of the business are actually affected because of that damage.
| Situation | What to check |
| Maximum indemnity period = 12 months; operations normalize after 5 months | The BI calculation ordinarily focuses on the actual affected period, subject to wording and time excess. |
| Business is still affected after 12 months but maximum selected was 12 months | The selected maximum generally caps the recoverable period even if commercial effects continue longer. |
| Factory is repaired in 4 months but sales remain weak for unrelated market reasons | The insurer may argue the later decline is not caused by insured damage. |
| Reinstatement is delayed because capital is unavailable | Some current wordings expressly exclude loss attributable to lack of sufficient capital for timely restoration. |
| Business never restarts | Coverage can become highly contentious; permanent discontinuance clauses and the ability to identify an actual interruption period become critical. |
Do not simply submit “12 months × monthly profit.” Build a dated interruption timeline: fire date, survey access, demolition, ordering replacement machinery, civil repairs, statutory permissions, trial production, partial restart, capacity ramp-up and return to normal operations.
A May 2026 NCDRC decision in Padam Cotton Yarns is a strong warning on this point. Under the wording and facts before it, the Commission held that permanent discontinuance and non-reinstatement left the interruption period indeterminate and defeated the LOP claim. That is a fact- and wording-specific decision, not a universal rule for every BI form, but it shows why restoration evidence matters.
“Gross Profit” in a BI Policy May Not Mean Your Accountant’s Gross Profit
One of the fastest ways to create a BI dispute is to lift a gross-profit number from the financial statements and assume the policy uses the same definition.
Different BI specifications define gross profit differently. Traditional consequential-loss wording can define it through net profit plus insured standing charges. Current package wordings can calculate it using turnover, closing stock/work in progress, opening stock/work in progress and specified uninsured working expenses.
So before arguing about the percentage, copy the policy’s exact definitions of Gross Profit, Net Profit, Turnover, Uninsured Working Expenses and Standing Charges into the claim worksheet. The accounting label used internally by the company is secondary.
| Term | Why it matters |
| Turnover | Usually money paid or payable for goods sold/services rendered; policy wording controls. |
| Gross Profit / Rate of Gross Profit | A policy-defined insurance measure used to convert lost turnover into insured loss. |
| Standing Charges | Fixed or continuing expenses included under some traditional LOP specifications; only insured/qualifying charges should be assumed. |
| Uninsured Working Expenses | Variable expenses excluded from the insured gross-profit calculation under some wordings. |
| Net Profit | May form part of the policy definition of Gross Profit in traditional forms; check the specification. |
| EBITDA / accounting gross margin | Useful business metrics, but not substitutes for the policy formula unless the wording says so. |
How a Turnover-Based BI Calculation Usually Works
A common turnover-basis calculation starts with the shortfall between Standard Turnover and actual Turnover during the indemnity period, then applies the Rate of Gross Profit. Increased Cost of Working may be added if it meets the policy test, while business expenses saved because of the interruption are deducted.
| Item | Illustrative amount |
| Adjusted standard turnover for affected period | ₹2,00,00,000 |
| Actual turnover during affected period | ₹80,00,000 |
| Turnover shortfall | ₹1,20,00,000 |
| Policy rate of gross profit | 30% |
| Loss of gross profit from turnover reduction | ₹36,00,000 |
That ₹36 lakh is not automatically the final claim. The settlement may still add qualifying increased cost of working, subtract savings, apply a time excess/deductible, apply BI underinsurance, account for turnover earned from other premises and make trend/special-circumstance adjustments.
The Trend Clause Can Move the Claim Up or Down
Standard Turnover often starts with the corresponding period before the loss, but the policy then allows adjustments for business trends, variations or special circumstances so the comparison reflects as nearly as practicable what would have happened without the damage.
That matters for a fast-growing company, a seasonal business, a unit that had just added capacity, a company with confirmed orders, or a business whose market was already falling before the fire.
| Claimant says turnover would have been higher | Insurer says turnover would have been lower |
| Confirmed purchase orders and long-term contracts | Pre-loss decline in monthly sales |
| New capacity commissioned before the damage | Customer cancellation unrelated to the fire |
| Documented price increase already implemented | Industry demand collapse or regulatory restriction |
| Historical seasonal pattern across several years | Loss of licence/order unrelated to the insured damage |
| Budget supported by actual pre-loss run rate | Persistent margin/volume deterioration before the event |
A budget prepared after the fire carries much less weight than a budget approved before the fire and supported by orders, production capacity and historical performance. Trend disputes should be evidence-led on both sides.
The current Property Guard wording also says turnover earned from goods sold or services rendered elsewhere for the benefit of the business during the indemnity period is taken into account. Moving work to another branch can reduce the turnover shortfall—but may simultaneously support an Increased Cost of Working claim if the extra spend meets the policy test.
Increased Cost of Working: Spending More to Lose Less
BI insurance can reward sensible loss mitigation. If the company rents temporary premises, hires substitute machinery, pays overtime or outsources production to keep sales moving, that extra expenditure may qualify as Increased Cost of Working (ICW), depending on the wording.
Current commercial wording commonly requires the expenditure to be necessary and reasonable and incurred for the sole purpose of avoiding or reducing the turnover loss caused by insured damage. It can also impose an economic limit linked to the gross profit saved.
| Item | Amount |
| Temporary outsourcing cost | ₹5,00,000 |
| Turnover loss avoided because of outsourcing | ₹20,00,000 |
| Rate of gross profit | 30% |
| Gross profit saved | ₹6,00,000 |
| Illustrative ICW potentially recoverable before other terms | ₹5,00,000 |
If the same temporary measure cost ₹8 lakh while it saved only ₹6 lakh of insured gross profit, a wording with this economic-limit structure may cap ordinary ICW at ₹6 lakh. Some policies contain separate extensions for additional increased cost beyond the ordinary economic limit; do not assume that extension exists.
Keep contemporaneous approval emails, quotations, invoices, transport records, temporary rent agreements, overtime sheets and a note showing what turnover would have been lost without the expenditure. An ICW claim is much stronger when the mitigation logic was documented while the business was making the decision.
Savings Are Part of the Calculation Too
A shutdown can reduce expenses. Power consumption may fall, casual labour may reduce, variable freight may disappear, or some insured standing charges may stop. BI wordings commonly deduct qualifying savings from the gross loss.
This is why claiming every pre-fire expense as a continuing standing charge can backfire. The better approach is to show what was actually incurred during the interruption and separate fixed continuing costs from expenses that genuinely ceased or reduced.
Turnover Basis, Output Basis and Departmental Results
Manufacturers sometimes find that turnover is a poor short-term measure because sales are maintained from finished-stock inventory even though production has collapsed. Some consequential-loss policies contain an Alternative Basis Clause allowing Output to substitute for Turnover when appropriate.
The policy may also contain an Accumulated Stock Clause so that a temporary maintenance of sales from pre-fire stock does not automatically erase the underlying production interruption.
Where a business has genuinely independent departments or plants with separately ascertainable trading results, a Departmental Clause may require or permit the calculation to be performed separately for the affected department.
In Manglam Organics v. New India Assurance, the NCDRC applied the departmental clause to the affected Resin Plant rather than blending the results with an independent Camphor Plant. The decision turned on that policy wording and the evidence of separate operations; it does not mean every multi-plant business can automatically carve out its best-performing unit.
The Delhi High Court’s Indo-Rama dispute shows the other side of the problem: choosing turnover versus output is not merely an accounting preference. The selected method must fit the policy and the indemnity principle rather than simply produce the larger number.
BI Underinsurance Is Different From Property Underinsurance
A business may insure its building and machinery adequately and still be underinsured for business interruption.
Under current turnover-based wording, if the BI sum insured is lower than the amount produced by applying the Rate of Gross Profit to Annual Turnover—appropriately scaled where the maximum indemnity period exceeds 12 months—the BI payment can be proportionately reduced.
| Required BI amount based on policy formula | ₹75,00,000 |
| BI sum insured | ₹60,00,000 |
| Insurance ratio | 80% |
| Otherwise admissible BI loss | ₹30,00,000 |
| Illustrative amount after BI underinsurance | ₹24,00,000 |
Do not confuse this with the average clause applied to buildings, machinery or stock. The denominator is different: property underinsurance looks at value at risk for the asset; BI underinsurance looks at the insured gross-profit/turnover exposure under the BI wording.
For the property side of the same claim, use our Average Clause and underinsurance guide to audit the material-damage valuation separately.
What If the Business Cannot Restart?
This is one of the hardest BI scenarios. The fire may destroy the productive assets, the property claim may be delayed, cash may run out and the owner may eventually decide that restarting is impossible.
Do not assume the maximum indemnity period automatically becomes payable because the business stayed closed. Some wordings cease or restrict BI liability if the business is permanently discontinued, and current policy forms can exclude interruption attributable to lack of sufficient capital for timely restoration.
The May 2026 Padam Cotton Yarns decision went further under the wording and facts before the NCDRC: because the assets were not reinstated and business did not recommence, the Commission held that the interruption period could not be properly crystallised and the LOP claim failed.
A claimant facing this issue should preserve evidence of every attempt to restart: finance applications, requests for on-account material-damage payment, machinery quotations, civil-repair orders, statutory permissions, landlord correspondence and board decisions. The cause of non-restart can become central to the BI dispute.
Separate Damage-Caused Loss From Other Business Problems
BI insurance does not turn every bad financial result after a fire into an insured loss. The turnover decline must be linked to the insured damage.
| Potentially damage-linked | Potentially independent of insured damage |
| Production stopped because insured machinery was destroyed | Industry-wide demand collapse |
| Orders delayed because the insured premises were unusable | Pre-existing customer insolvency |
| Extra freight from temporary outsourced production | Unrelated loss of licence after repairs were complete |
| Reduced capacity during reinstatement | Management decision to exit an unprofitable product line |
| Temporary relocation expense to preserve sales | Permanent market loss after operations could have resumed |
The cleanest claim file explains the interruption month by month. If the cause changes halfway through the period, say so. Trying to attribute every later loss to the fire can undermine the stronger part of the claim.
Documents That Usually Decide a Business-Interruption Claim
| Document / data | Why it matters |
| BI policy schedule, specification and endorsements | Gross-profit definition, maximum indemnity period, time excess, sum insured and special clauses. |
| Underlying material-damage policy and claim decision | Establishes the insured damage trigger and affected property. |
| BI survey report and calculation workbook | Shows baseline, rates, trend adjustments, savings, ICW and underinsurance. |
| Audited financial statements for prior years | Historical profitability and policy-defined gross-profit reconstruction. |
| Monthly sales / GST returns / invoices | Actual and pre-loss turnover pattern. |
| Production / output records | Useful where output basis or accumulated stock is relevant. |
| Budgets and forecasts prepared before the loss | Evidence for growth or trend adjustment. |
| Confirmed orders / contracts / cancellation records | Evidence of demand that would likely have existed but for the damage. |
| Payroll, rent, finance and utility records | Whether standing/continuing charges were actually incurred or saved. |
| ICW invoices and mitigation decision records | Proof that extra expenditure was necessary, reasonable and turnover-saving. |
| Repair and reinstatement chronology | Actual interruption period and mitigation effort. |
| Other-premises / outsourcing sales records | Turnover preserved elsewhere must be accounted for. |
If the insurer keeps asking for accounts or operational records without identifying the exact deficiency, use our claim query and deficiency-letter response guide to respond document-by-document and preserve an audit trail.
Ten Questions to Put to the Insurer or BI Surveyor
| 1 | What exact material-damage event and policy clause are being treated as the BI trigger? |
| 2 | What actual indemnity period has been used, and why does it start and end on those dates? |
| 3 | What is the policy definition of Gross Profit and what rate has been applied? |
| 4 | What Standard Turnover has been selected for each affected month? |
| 5 | What trend or special-circumstance adjustments have been made, upward or downward, and on what evidence? |
| 6 | What turnover from other premises, accumulated stock or outsourced production has been credited against the claim? |
| 7 | Which Increased Cost of Working items were accepted or rejected, and what economic-limit calculation was used? |
| 8 | What savings or ceased expenses were deducted? |
| 9 | Has BI underinsurance/average been applied; if yes, what Annual Turnover and gross-profit exposure were used as the denominator? |
| 10 | If departmental or output basis was rejected, what policy wording and financial evidence support that decision? |
When a BI Claim Challenge Is Stronger
The insurer accepts material damage but uses an interruption period that ends before the damaged operation could reasonably restart, without engaging with the repair chronology.
The surveyor uses a consolidated business result even though the policy contains a departmental clause and independent trading results for the affected unit are reliably ascertainable.
The insurer ignores a documented pre-loss growth trend, confirmed orders or commissioned capacity while mechanically using last year’s turnover.
Qualifying mitigation spend is rejected without testing how much turnover loss it actually avoided.
The BI sum insured is treated as underinsured using a denominator that does not match the policy-defined gross-profit formula.
The calculation mixes accounting gross profit, policy gross profit and EBITDA without explaining which contract definition governs.
The insurer gives a final BI figure without disclosing the turnover baseline, trend adjustment, rate of gross profit, savings, ICW, time excess and underinsurance steps.
When the Claim May Be Difficult to Improve
The underlying physical damage is not indemnifiable under the linked policy and the BI wording expressly requires indemnifiable material damage.
The company claims the full maximum indemnity period but cannot show when and how insured damage actually affected business results.
The claim relies mainly on a post-loss forecast with no pre-loss orders, historical trend, capacity or budget evidence.
The business stayed closed permanently and the wording contains a permanent-discontinuance restriction or requires a measurable interruption period.
The claimed ICW did not preserve turnover, was not reasonably necessary, or was incurred for expansion/improvement rather than mitigation.
Sales were maintained from other premises or accumulated stock but the claim ignores that turnover.
The claimant treats every pre-loss expense as a continuing standing charge even though significant costs actually stopped.
How to Appeal a Rejected or Short-Settled BI Claim
Do not start with “our CA says the loss is ₹X crore.” Start with the policy mechanics. Recreate the insurer’s worksheet using the same headings as the contract, then mark the first point where you disagree.
If the dispute is the indemnity period, attach the repair/restart chronology. If it is trend, attach pre-loss orders and monthly run-rate. If it is gross-profit rate, reconcile the policy definition to audited accounts. If it is ICW, show the turnover saved by each expense.
Where the surveyor has made a technical or accounting choice, challenge that choice with a policy clause plus evidence rather than simply presenting a higher alternative calculation.
Ask the insurer’s grievance team for a reasoned response to each disputed component and keep the BI dispute separate from the material-damage amount unless the two issues genuinely depend on each other.
If the insurer maintains the rejection or calculation after internal grievance, compare the escalation options in our Bima Bharosa vs Insurance Ombudsman guide before choosing the next forum.
Be Careful With a Full-and-Final BI Settlement
BI claims often take longer than the property-damage claim because the final turnover shortfall cannot be known until the interruption period develops. An on-account payment is not the same thing as a final calculation.
If the insurer offers a final amount while the trend, indemnity-period or gross-profit calculation is disputed, preserve your written objection and the calculation you say is correct before signing any full-and-final document.
Before signing a disputed settlement, review our full-and-final discharge voucher guide so the objection is documented before the payment is treated as closure.
What the Key Indian Decisions Add
| Decision | Practical point |
| New India Assurance v. Zuari Industries (Supreme Court, 2009) | Policy wording and proximate cause matter; courts should not add words such as a requirement for a 'sustained' fire where the policy says fire. |
| Nagarjuna Agrichem v. Oriental Insurance (Delhi High Court, 2018) | LOP/consequential loss sits on top of material-damage cover and is contractually linked to it. |
| Indo-Rama Synthetics v. IFFCO Tokio (Delhi High Court, 2019) | Turnover versus output method must be justified under the policy and the indemnity principle, not selected merely because it produces a preferred number. |
| Manglam Organics v. New India Assurance (NCDRC, 2021) | Under the wording and evidence there, departmental results for the independently affected Resin Plant were relevant; the Commission reproduced alternative-basis, accumulated-stock and departmental clauses. |
| Padam Cotton Yarns v. New India Assurance (NCDRC, 29 May 2026) | Under that wording/facts, permanent discontinuance and non-reinstatement meant no determinable interruption period and the LOP claim failed. |
None of these decisions replaces the current policy schedule in your hand. BI disputes are unusually clause-sensitive: two companies can suffer similar fires and still have different outcomes because their triggers, indemnity periods, departmental clauses, output clauses, time excesses and sum insured are different.
How Tatkal Claims Can Help
Tatkal Claims can review the material-damage decision, BI wording, surveyor workbook, audited accounts, monthly turnover/output, budgets, orders, standing-charge records, mitigation expenses and reinstatement chronology to identify where the insurer’s calculation departs from the contract or the evidence.
Where a documented issue exists, assistance can include rebuilding the BI calculation, organising the accounting and operational evidence, preparing a clause-by-clause representation to the insurer and escalating an unresolved grievance through the appropriate forum. We cannot promise a BI payout: the claimant must still prove an insured trigger, actual interruption and a loss that fits the policy formula.
Frequently Asked Questions
Frequently asked questions
Is business interruption insurance the same as fire insurance?
No. Fire/material-damage insurance pays for insured physical damage to property. Business interruption or loss-of-profit insurance covers defined financial loss caused by interruption or interference with the business following insured damage, subject to its own calculation and limits.
Does an admitted fire claim automatically mean the loss-of-profit claim must be paid?
No. Admission of the material-damage trigger is important, but the BI claimant must still prove the actual interruption period, turnover/output impact, policy-defined gross-profit rate, mitigation costs, savings and other calculation inputs.
If my maximum indemnity period is 12 months, can I claim 12 months automatically?
Usually no. The maximum indemnity period is a ceiling. The recoverable period is generally the period during which the business results were actually affected by insured damage, subject to the wording, time excess and maximum selected.
What is Standard Turnover in a business interruption claim?
It is commonly the turnover for the corresponding pre-loss period used as the starting benchmark for the indemnity period, then adjusted where the policy permits for business trend and special circumstances so it approximates the result that would have occurred without the insured damage.
Is the gross profit in my audited P&L the same as insured Gross Profit?
Not necessarily. BI policies contain their own definitions. Some traditional wordings define insured gross profit through net profit plus insured standing charges; other forms use turnover and stock less specified uninsured working expenses. Use the policy definition, not the accounting label alone.
Can temporary rent or outsourcing cost be claimed?
Potentially, as Increased Cost of Working, if the policy covers it and the expenditure was necessary and reasonable to avoid or reduce turnover loss caused by insured damage. Ordinary ICW can also be subject to an economic limit based on the gross profit saved.
Can the insurer deduct expenses that stopped during the shutdown?
Yes, many BI wordings deduct savings in charges and expenses that cease or reduce because of the damage. The dispute should focus on which expenses actually stopped and whether they fall within the policy calculation.
Can I use production loss instead of turnover loss?
Only where the policy wording supports an output or alternative basis and the method fits the facts. Some policies allow output to replace turnover in appropriate cases, but the method must still comply with the indemnity principle and the specific clause.
Can business interruption be underinsured even if my factory building is fully insured?
Yes. BI underinsurance is tested against the business-interruption exposure under the BI formula, such as the rate of gross profit applied to annual turnover, rather than the replacement value of the building or machinery.
What is the most important evidence in a disputed BI claim?
There is rarely one document. The strongest file combines the BI wording and schedule, the underlying material-damage decision, the surveyor’s BI workbook, monthly turnover/output data, audited accounts, pre-loss budgets/orders, mitigation expenses and a dated restoration/restart chronology.
Sources and Methodology
Disclaimer: This guide explains business-interruption/loss-of-profit insurance in India in general terms. BI policies are highly wording-specific. The result in a particular claim depends on the material-damage trigger, schedule, specification, endorsements, maximum indemnity period, time excess, gross-profit definition, turnover/output basis, trend clause, departmental clause, savings, Increased Cost of Working, underinsurance and the evidence of actual interruption. Court and consumer-forum decisions cited are fact- and policy-specific. This is not legal, accounting or loss-adjusting advice for a specific claim.