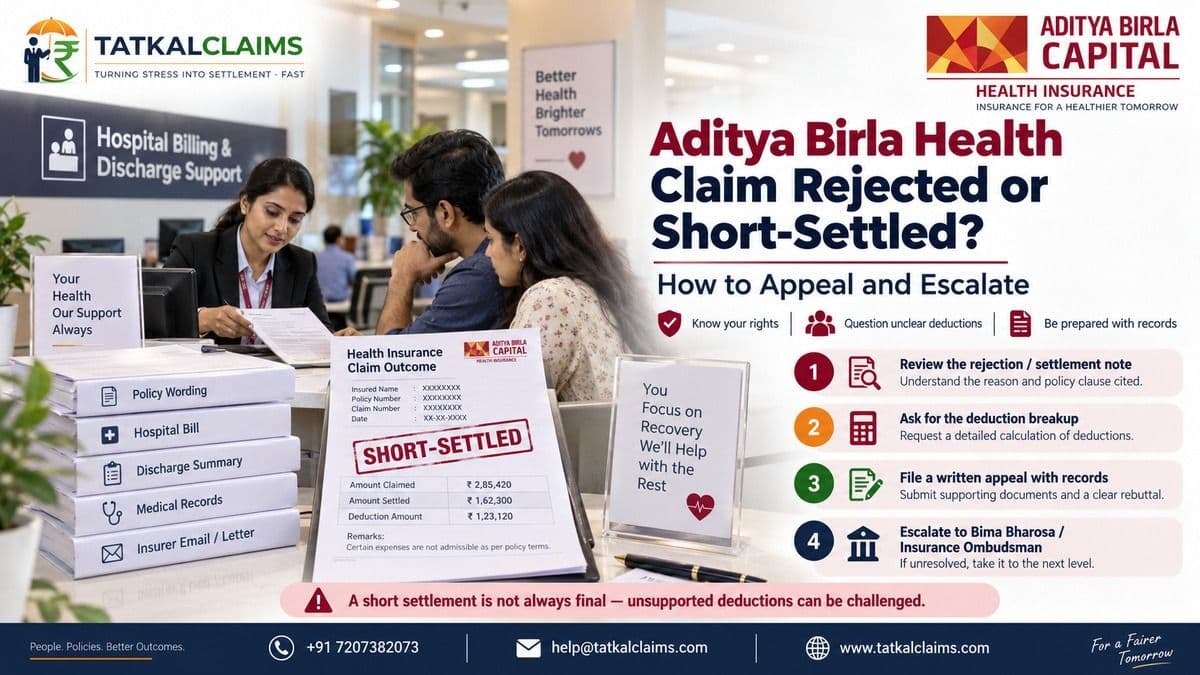
If Aditya Birla Health Insurance has rejected your claim, reduced the amount payable, delayed settlement or denied a cashless request, the insurer's first decision does not necessarily end the matter.
This is a health-only claim guide, so the appeal should be built around the medical basis of the decision, proposal disclosures, policy wording, document completeness and the insurer's published health-claim service stages.
A useful appeal should address Aditya Birla Health's exact reason. Identify the policy clause, medical conclusion, documentation issue, waiting period, alleged non-disclosure or deduction relied upon and answer that point with evidence.
The strongest grievance is not a general request for reconsideration. It is a structured record showing what the insurer decided, why you disagree, what document or policy wording supports your position and what precise correction you want.
First: Identify What Happened to Your Aditya Birla Health Claim
| Claim problem | What to obtain | What the appeal should examine |
|---|---|---|
| Claim rejected completely | Rejection/repudiation letter | Exact exclusion, waiting period, medical conclusion or factual basis |
| Claim short-settled | Settlement statement | Each deduction and the policy provision relied upon |
| Cashless request denied | Pre-authorisation response | Whether only cashless was declined or the underlying claim was rejected |
| Reimbursement delayed | Acknowledgement and document trail | Date the final necessary documents were submitted |
| PED/non-disclosure rejection | Proposal form and medical records | What was asked, known, disclosed and relied upon |
| Repeated document query | Earlier submission proof | Whether the requested document was already supplied |
For the wider insurer-neutral framework, use Tatkal Claims' Insurance Claim Rejected? What to Do Next – Complete Guide for India.
Step 1: Obtain the Exact Rejection or Deduction Reason
Before appealing, obtain Aditya Birla Health's written claim decision. For a rejected claim, identify the exact clause and factual basis. For a short settlement, obtain the calculation showing how the insurer moved from the amount claimed to the amount paid.
For a health dispute, identify whether the decision concerns a waiting period, pre-existing disease, alleged non-disclosure, exclusion, medical necessity, sub-limit, co-payment, deductible, room eligibility or document deficiency.
Address the insurer's reasoning line by line. If the reason is unclear, ask for clarification in writing before building a long appeal around assumptions.
Step 2: Register the Complaint With Aditya Birla Health
Aditya Birla Health publishes Level 1 support at 1800 270 7000 and care.healthinsurance@adityabirlacapital.com. Preserve the complaint reference and the acknowledgement of every claim document submitted.
A written complaint should identify the policy number, claim number, relevant dates, amount claimed, amount rejected or deducted, Aditya Birla Health's stated reason, the policy clause in dispute, the key supporting evidence and the specific remedy requested.
Always preserve the acknowledgement or interaction reference. If documents are re-submitted, record both the original submission date and the later re-submission so the chronology remains clear.
Step 3: Escalate to Head – Customer Care
If Level 1 does not resolve the dispute, Aditya Birla Health publishes carehead.healthinsurance@adityabirlacapital.com for Level 2 review. Forward the first complaint and explain which rejection reason, deduction or delay remains unresolved.
Do not restart the story at every level. Forward the earlier complaint and response, then identify the precise unresolved issue, the evidence already supplied and the correction still requested.
Step 4: Escalate to the Grievance Redressal Officer
For the final published internal review, Aditya Birla Health lists gro.healthinsurance@adityabirlacapital.com. Keep the representation concise and attach the policy clause, medical evidence and earlier responses that directly support the challenge.
Do not restart the story at every level. Forward the earlier complaint and response, then identify the precise unresolved issue, the evidence already supplied and the correction still requested.
Separate Channel for Senior Citizens
Aditya Birla Health publishes seniorcitizen.healthinsurance@adityabirlacapital.com for senior citizens. Keep the same claim chronology and reference numbers when using this route.
How Long Should an Aditya Birla Health Grievance Take?
Aditya Birla Health's current Service TAT lists grievance acknowledgement within 1 day and grievance resolution within 15 days from receipt of the complaint. Its separate grievance policy also states full closure or resolution within 15 calendar days. Use the current service page and acknowledgement received in your own case when documenting delay.
IRDAI's Bima Bharosa FAQ separately states that an insurance company should resolve a grievance within 15 days of receipt.
The Insurance Ombudsman uses a different insurer-first threshold: if the insurer does not respond within 30 days, the no-response route may become available, subject to the other eligibility conditions.
Aditya Birla Health Claim Disputes
Aditya Birla Health separately tracks cashless pre-authorisation, discharge authorisation and reimbursement processing. Do not combine those stages into one settlement deadline; if delay is disputed, identify the specific stage and the date on which complete information was submitted.
| Health service | Published / stated TAT |
|---|---|
| Cashless pre-authorisation | 1 hour |
| Discharge authorisation | 3 hours |
| Reimbursement payment | Usually within 15 working days from document submission, subject to requirements and policy terms |
Aditya Birla Health publishes more than one claim-timing benchmark for different contexts. Its reimbursement page says payment is usually completed within 15 working days from document submission, while its Service TAT lists 10 days from receipt of the last necessary document where no investigation is required and 21 days where investigation is required. These should be described as separate published benchmarks, not one universal deadline.
These service stages do not guarantee that every amount requested by the hospital or claimant is payable. Admissibility still depends on the policy wording, medical facts, exclusions, limits and required documents.
Cashless Rejection Is Not Necessarily Final Claim Rejection
A cashless denial concerns the settlement mechanism at that stage. It should not automatically be treated as final repudiation of the underlying health claim. Ask Aditya Birla Health to state the reason in writing and check whether reimbursement remains available under the policy.
Use Tatkal Claims' Cashless Health Insurance Claim Rejected? How to File a Reimbursement Claim guide for the broader reimbursement route.
Pre-Existing Disease and Non-Disclosure Rejections
If Aditya Birla Health relies on a pre-existing condition or non-disclosure, obtain the proposal form or declaration record, prior and current medical records, the rejection letter and the relevant policy wording. The review should compare what was asked, what the insured knew, what was disclosed and how the alleged non-disclosure relates to the claim.
Use Tatkal Claims' Health Insurance Claim Rejected for Pre-Existing Disease guide for the wider framework.
Short-Settled Health Claims
If Aditya Birla Health admits the claim but pays less than the amount claimed, request a line-by-line settlement calculation. Separate co-pay, deductible, room eligibility, proportionate deduction, sub-limits, exclusions, non-medical items and medical-admissibility disputes because each may require a different response.
Use Tatkal Claims' Health Insurance Claim Short-Settled? How to Check and Challenge Deductions guide to analyse the settlement.
How to Structure a Strong Aditya Birla Health Appeal
Start with a short factual summary: policy number, claim number, hospitalisation dates, amount claimed, amount paid if any and the date of Aditya Birla Health's decision.
Then quote the insurer's exact rejection clause, medical conclusion, waiting period, deduction or document allegation. Explain precisely why you disagree and attach the medical or policy evidence that answers that point.
Finish with a specific remedy: reconsider the repudiation, reverse named deductions, consider identified medical records, release an admitted amount, confirm document completeness or issue a reasoned written decision.
A focused representation is usually more useful than a long narrative that does not address the insurer's actual reasoning.
Escalating Through Bima Bharosa
IRDAI states that a policyholder should first approach the insurer's grievance mechanism, submit the grievance in writing with supporting documents and obtain written acknowledgement.
IRDAI's current Bima Bharosa FAQ states that the insurance company should resolve the complaint within 15 days of receipt. If the grievance is unresolved within the prescribed period, or the response is unsatisfactory, the policyholder can use Bima Bharosa and IRDAI's grievance channels.
Use Tatkal Claims' Bima Bharosa vs Insurance Ombudsman guide before deciding which escalation route fits the dispute.
When to Approach the Insurance Ombudsman
The Council for Insurance Ombudsmen says that you should first complain to the insurer.
If you are dissatisfied with the insurer's response, or there is no response within 30 days, you may approach the Insurance Ombudsman subject to the other eligibility rules.
The current procedure states that the claim value including relevant expenses must not exceed ₹50 lakh, the complaint generally must be filed within one year, and the same subject matter should not already be before or disposed of by a court, consumer forum or arbitrator.
Claims involving delay, partial settlement or complete repudiation are among the matters the Ombudsman can consider.
See Tatkal Claims' Insurance Ombudsman Complaint Process in India guide before filing.
7-Day Action Plan After an Aditya Birla Health Claim Rejection
| Day | Action | Output to preserve |
|---|---|---|
| Day 1 | Obtain the written rejection, deduction or delay position | Decision letter / claim status |
| Day 2 | Collect policy wording, proposal/declarations and the settlement or assessment calculation | Policy and calculation file |
| Day 3 | Build the medical-evidence and document-submission chronology | Indexed medical and claim file |
| Day 4 | Write the first insurer grievance around the exact disputed reason | Complaint and acknowledgement |
| Day 5 | Reconcile every deduction or disputed factual finding | Issue-by-issue response |
| Day 6 | Prepare the next internal escalation using the same chronology | Escalation-ready file |
| Day 7 | Check Bima Bharosa / Ombudsman eligibility and deadlines if the internal route is not resolving the issue | External-escalation checklist |
Keep the dispute in writing. Telephone calls may help with follow-up, but they should not replace a documentary record.
Can Tatkal Claims Help With an Aditya Birla Health Claim Dispute?
Tatkal Claims assists policyholders dealing with rejected, delayed and short-settled health-insurance claims. Depending on the case, assistance may include reviewing Aditya Birla Health's reasoning, analysing policy wording, organising medical evidence and deduction calculations, preparing a structured representation and preparing the dispute for Bima Bharosa or the Insurance Ombudsman.
No claim outcome can be guaranteed. Every claim depends on its own policy wording, facts, disclosures, evidence and applicable rules.
Frequently asked questions
Where should I first raise an Aditya Birla Health Insurance grievance?
Use Level 1 at care.healthinsurance@adityabirlacapital.com or 1800 270 7000 and preserve the grievance reference.
What is the next escalation?
Escalate to carehead.healthinsurance@adityabirlacapital.com and then gro.healthinsurance@adityabirlacapital.com if needed.
Is there a senior-citizen channel?
Yes. Aditya Birla Health publishes seniorcitizen.healthinsurance@adityabirlacapital.com.
Can a cashless denial still be filed as reimbursement?
Potentially yes, subject to policy terms and claim facts. Preserve the cashless decision and complete hospital records.
What should I do if my health claim is short-settled?
Request the full deduction calculation and compare every deduction with the policy wording.
Can I escalate through Bima Bharosa?
Yes, after first using the insurer's grievance mechanism and subject to the applicable IRDAI framework.
Can I approach the Insurance Ombudsman?
Potentially yes, after first approaching the insurer and subject to the Ombudsman's eligibility rules.
What should I do if Aditya Birla Health asks for the same document again?
Resubmit it if practical, but also refer to the earlier submission date and acknowledgement so the claim chronology shows that the document had already been provided.
How should I challenge a medical rejection?
Ask for the medical and policy basis in writing, then compare it with the treating doctor's records, diagnosis, proposal disclosures and the exact exclusion or waiting period relied upon.
What should I preserve from the ABHI claim tracker?
Keep the acknowledgement number, status history, document-upload dates, query dates and your responses, because those records can help establish where a delay or dispute arose.
Official Sources
Disclaimer: This article provides general information about health-insurance claim grievance and escalation processes in India. Policy wording, medical facts, documents and applicable rules differ from case to case. It does not guarantee that a rejected, delayed or short-settled claim will be reversed.