A Zuno claim file can become confusing before you even reach the merits of the rejection because older policies and correspondence may still carry the Edelweiss General name. Do not split those papers into two separate histories—the old and new branding can belong to the same continuing policy or claim record.
Zuno General Insurance Limited was formerly Edelweiss General Insurance Company Limited. If your policy started, renewed or generated claim correspondence around that transition, keep the older policy schedule, endorsements, emails and claim references together with the current Zuno communications.
Once the chronology is clean, focus on the actual claim issue. In health claims that may be a medical exclusion, waiting period, non-disclosure allegation or deduction; in motor claims it may be the survey assessment, repair-versus-replacement decision, depreciation, IDV or causation.
At Tatkal Claims, we would first check whether the insurer's final reason can be traced consistently through the policy, claim correspondence and evidence. A change in company name should not make you lose the earlier paper trail, and a grievance should make that continuity obvious to whoever reviews it next.
First: Identify What Happened to Your Zuno Claim
| Claim problem | What to obtain | What the appeal should examine |
|---|---|---|
| Claim rejected completely | Rejection/repudiation letter | Exact exclusion, condition or factual basis |
| Claim short-settled | Settlement sheet | Each deduction and supporting policy provision |
| Cashless request denied | Pre-authorisation response | Whether cashless alone was declined or the health claim itself was rejected |
| Health reimbursement delayed | Claim acknowledgement and document trail | Date the final necessary documents were submitted |
| PED/non-disclosure rejection | Proposal form and medical records | What was asked, known and disclosed |
| Motor repair amount reduced | Survey assessment and garage estimate | Accident-related damage, depreciation and excluded items |
| Vehicle theft claim delayed | FIR, police papers and claim correspondence | Documentation and investigation requirements |
| Total-loss dispute | IDV, survey report and repair estimate | CTL threshold, salvage and settlement calculation |
For the wider insurer-neutral framework, use Tatkal Claims' Insurance Claim Rejected? What to Do Next – Complete Guide for India.
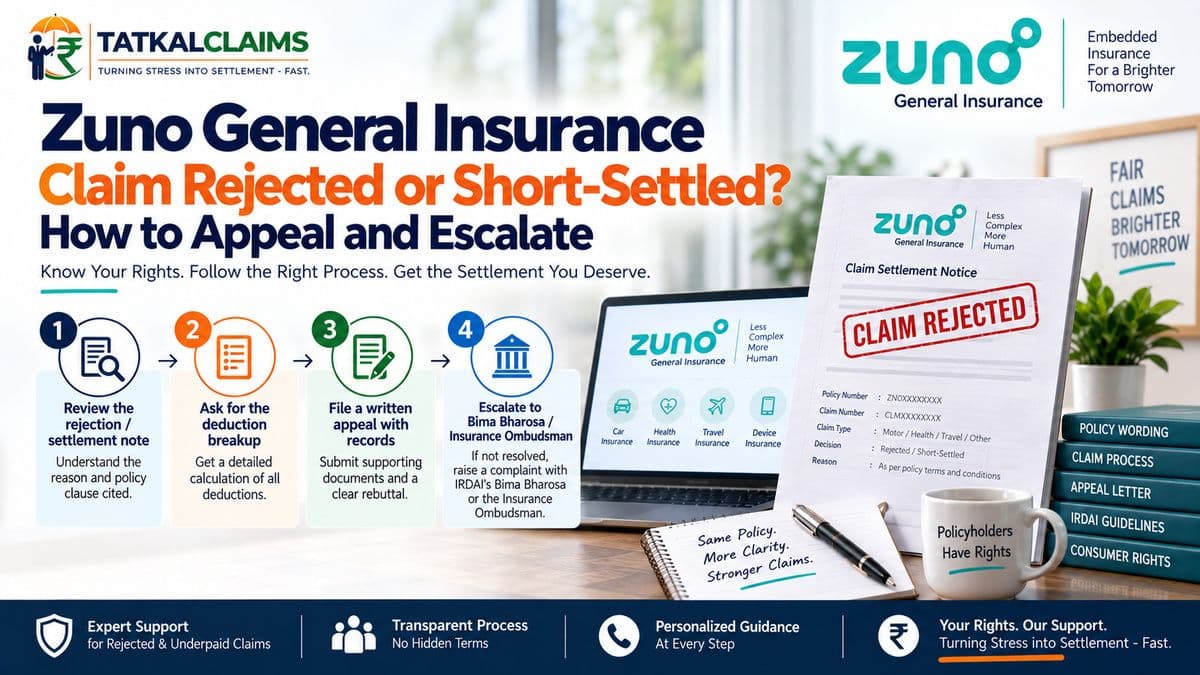
Step 1: Obtain the Exact Rejection or Deduction Reason
Before appealing, obtain Zuno's written claim decision. For a rejected claim, identify the exact clause and factual basis. For a short settlement, obtain the calculation showing how the insurer moved from the amount claimed to the amount paid.
For a motor dispute, request the survey or inspection assessment where relevant. For a health dispute, identify whether the decision concerns a waiting period, pre-existing disease, alleged non-disclosure, exclusion, sub-limit, co-payment, deductible or another contractual restriction.
Address the insurer's reasoning line by line. If the reason is unclear, ask for clarification in writing before building a long appeal around assumptions.
Step 2: Register the Complaint With Zuno
Start with Zuno customer support at support@hizuno.com, toll-free 1800 12000 or 022 423 12000. Ask for a written complaint or interaction reference and keep it with the claim file.
A written complaint should identify the policy number, claim number, relevant dates, amount claimed, amount rejected or deducted, Zuno's stated reason, the policy clause in dispute, the key supporting evidence and the specific remedy requested.
Always preserve the acknowledgement or interaction reference. If documents are re-submitted, record both the original submission date and the later re-submission so the chronology remains clear.
Step 3: Escalate Through Zuno's Formal Grievance Channel
If customer support does not resolve the dispute, Zuno publishes grievance@hizuno.com and 1800 120 216216 for formal grievance escalation. Forward the earlier complaint, the claim decision and the specific point that remains unresolved.
At the formal grievance stage, attach the earlier service complaint and response and make the unresolved point explicit. If an older document carries the Edelweiss General name, label it by date and policy or claim number so the reviewer can see immediately why it belongs to the same file.
Step 4: Escalate to the Grievance Redressal Officer
If the grievance remains unresolved, Zuno publishes grievanceofficer@hizuno.com for its Grievance Redressal Officer. Keep the escalation focused on the exact claim error, the evidence already submitted and the remedy still requested.
Separate Channel for Senior Citizens
Zuno publishes senior.citizen@hizuno.com and 022 4231 2001 for senior-citizen support. Use the same policy number, claim number and chronology so the special channel remains connected to the existing dispute.
How Long Should a Zuno Grievance Take?
Zuno's current policyholder-protection material states that complaints are addressed within 14 days.
IRDAI's Bima Bharosa FAQ separately states that an insurance company should resolve a grievance within 15 days of receipt.
The Insurance Ombudsman uses a different insurer-first threshold: if the insurer does not respond within 30 days, the no-response route may become available, subject to the other eligibility conditions.
Zuno Health Claim Disputes
Zuno's current claims process supports both cashless and reimbursement health claims. If a cashless request is declined, preserve the hospital's pre-authorisation request, Zuno's response, medical records, discharge summary, final bills and receipts so the reimbursement route can be assessed separately.
Cashless Rejection Is Not Necessarily Final Claim Rejection
A cashless denial concerns the settlement mechanism at that stage. It should not automatically be treated as final repudiation of the underlying health claim. Ask Zuno to state the reason in writing and check whether reimbursement remains available under the policy.
Use Tatkal Claims' Cashless Health Insurance Claim Rejected? How to File a Reimbursement Claim guide for the broader reimbursement route.
Pre-Existing Disease and Non-Disclosure Rejections
If Zuno relies on a pre-existing condition or non-disclosure, obtain the proposal form or declaration record, prior and current medical records, the rejection letter and the relevant policy wording. The review should compare what was asked, what the insured knew, what was disclosed and how the alleged non-disclosure relates to the claim.
Use Tatkal Claims' Health Insurance Claim Rejected for Pre-Existing Disease guide for the wider framework.
Short-Settled Health Claims
If Zuno admits the claim but pays less than the amount claimed, request a line-by-line settlement calculation. Separate co-pay, deductible, room eligibility, proportionate deduction, sub-limits, exclusions, non-medical items and medical-admissibility disputes because each may require a different response.
Use Tatkal Claims' Health Insurance Claim Short-Settled? How to Check and Challenge Deductions guide to analyse the settlement.
Zuno Motor Claim Disputes
For motor disputes, preserve the accident photographs, claim intimation, registration certificate, driving licence, garage estimate, survey communications, repair invoice and settlement calculation. Ask Zuno to identify the survey or policy basis for every disputed repair item or deduction.
Accident Repair and Survey Disputes
If Zuno's approved repair amount is below the garage estimate, compare the survey or inspection assessment with the estimate item by item. Separate accident-related damage from depreciation, deductibles, consumables, excluded damage, salvage and repair-versus-replacement decisions.
Total Loss and Constructive Total Loss
For a total-loss or constructive-total-loss dispute, obtain the IDV, survey report, repair estimate, salvage assessment, policy wording and settlement calculation before challenging the decision.
Use Tatkal Claims' Car Total Loss vs Constructive Total Loss: 75% IDV Rule, Salvage & Claim Settlement guide for the wider framework.
Vehicle Theft Claims
Preserve the FIR, keys, registration documents, police final report or non-traceable report where applicable, financier documents and every insurer communication. If the claim is delayed for documents, ask the insurer to identify the exact outstanding requirement in writing.
See Tatkal Claims' Car Stolen? Insurance Claim Process, Documents, FIR, Non-Traceable Certificate & Delayed Intimation guide for the broader process.
How to Structure a Strong Zuno Appeal
Start with a short factual summary: policy number, claim number, date of hospitalisation or loss, amount claimed, amount paid if any and date of Zuno's decision.
Then quote the insurer's exact rejection clause, medical conclusion, survey or assessment finding, deduction or document allegation. Explain precisely why you disagree and attach the evidence that answers that point.
Finish with a specific remedy: reconsider the repudiation, reverse named deductions, consider identified medical or loss evidence, provide the survey or assessment basis, release an admitted amount or issue a reasoned written decision.
The appeal should read like one continuous claim file, not two stories divided by the insurer's old and new names. Put the disputed clause or assessment first, then the evidence that contradicts it and the exact correction you are asking Zuno to make.
Escalating Through Bima Bharosa
IRDAI states that a policyholder should first approach the insurer's grievance mechanism, submit the grievance in writing with supporting documents and obtain written acknowledgement.
IRDAI's current Bima Bharosa FAQ states that the insurance company should resolve the complaint within 15 days of receipt. If the grievance is unresolved within the prescribed period, or the response is unsatisfactory, the policyholder can use Bima Bharosa and IRDAI's grievance channels.
Use Tatkal Claims' Bima Bharosa vs Insurance Ombudsman guide before deciding which escalation route fits the dispute.
When to Approach the Insurance Ombudsman
The Council for Insurance Ombudsmen says that you should first complain to the insurer.
If you are dissatisfied with the insurer's response, or there is no response within 30 days, you may approach the Insurance Ombudsman subject to the other eligibility rules.
The current procedure states that the claim value including relevant expenses must not exceed ₹50 lakh, the complaint generally must be filed within one year, and the same subject matter should not already be before or disposed of by a court, consumer forum or arbitrator.
Claims involving delay, partial settlement or complete repudiation are among the matters the Ombudsman can consider.
See Tatkal Claims' Insurance Ombudsman Complaint Process in India guide before filing.
7-Day Action Plan After a Zuno Claim Rejection
| Day | Action | Output to preserve |
|---|---|---|
| Day 1 | Obtain the written rejection, deduction or delay position | Decision letter / claim status |
| Day 2 | Collect policy wording, proposal/declarations and the settlement or assessment calculation | Policy and calculation file |
| Day 3 | Build the medical, motor, crop or other loss-evidence chronology | Indexed evidence set |
| Day 4 | Write the first insurer grievance around the exact disputed reason | Complaint and acknowledgement |
| Day 5 | Reconcile every deduction or disputed factual finding | Issue-by-issue response |
| Day 6 | Prepare the next internal escalation using the same chronology | Escalation-ready file |
| Day 7 | Check Bima Bharosa / Ombudsman eligibility and deadlines if the internal route is not resolving the issue | External-escalation checklist |
Keep the dispute in writing. Telephone calls may help with follow-up, but they should not replace a documentary record.
What Tatkal Claims Would Check First in a Zuno Claim Dispute
We would first reconcile the policy and claim chronology, especially where older papers use the Edelweiss General name. After that, the review becomes claim-specific: medical records and policy restrictions for a health dispute, or survey findings, repair evidence, IDV and settlement calculations for a motor dispute. The objective is to separate a documentation or continuity problem from the actual coverage dispute before choosing the escalation route.
No claim outcome can be guaranteed. Every claim depends on its own policy wording, facts, disclosures, evidence and applicable rules.
Frequently asked questions
Can a cashless denial still be filed as reimbursement?
Potentially yes, subject to policy terms and claim facts. Preserve the cashless decision and complete hospital records.
What should I do if a motor repair claim is reduced?
Obtain the survey assessment and compare it item by item with the garage estimate, repair invoice and policy terms.
What should I request if Zuno says documents are incomplete?
Ask Zuno to identify every outstanding document in writing and preserve the reply together with proof of earlier submissions.
What should I request for a short-settled motor claim?
Ask for the survey assessment and settlement calculation, then compare each deduction with the garage estimate, repair evidence and policy wording.
Should older Edelweiss General documents be kept?
Yes. If the policy or earlier claim papers use the former Edelweiss General name, keep them with the current Zuno correspondence so the full claim history remains clear.
Need Help Reviewing a Zuno Health Claim Rejection?
Tatkal Claims can review the written health-claim decision, cashless or reimbursement records, proposal disclosures, medical evidence, policy wording, insurer queries and grievance responses to identify the issue that may need to be challenged. Keep the claim number and written Zuno decision ready; no claim outcome can be guaranteed.
Official Sources
Disclaimer: This article provides general information about insurance claim grievance and escalation processes in India. Policy wording, endorsements, facts and applicable rules differ from case to case. It does not guarantee that a rejected, delayed or short-settled claim will be reversed.