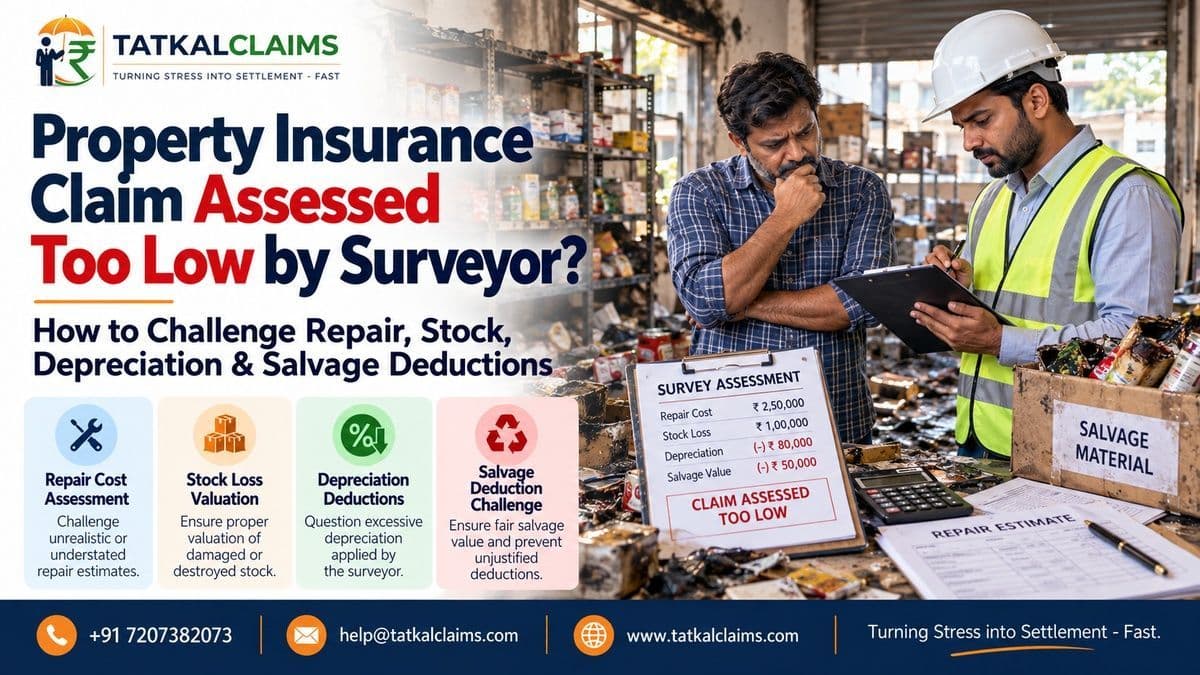
The insurer is not denying that the fire happened. The surveyor has inspected the premises. Photographs exist, invoices have been submitted and the damaged machinery or stock is right there. Yet the assessment sheet arrives with a number that feels disconnected from the actual loss.
A ₹40 lakh repair estimate becomes ₹18 lakh. Stock claimed at ₹25 lakh is assessed at ₹9 lakh. Labour rates are cut, quantities are reduced, depreciation is loaded, salvage is increased, or part of the repair scope simply disappears from the final working.
That is a different dispute from outright claim rejection. The argument is not “please reconsider sympathetically.” It is: which quantity, rate, policy clause, valuation basis, depreciation percentage, salvage figure or document led to the reduced assessment—and is that step supportable?
What a Surveyor Is Supposed to Do in a Property Claim
IRDAI describes a licensed surveyor and loss assessor as an insurance intermediary who investigates, manages, quantifies, validates and deals with losses on behalf of an insurer or insured. The work must be carried out with competence, objectivity and professional integrity.
The 2015 Surveyors and Loss Assessors Regulations go further. A surveyor’s duties include inspecting and re-inspecting damaged property, examining the cause and extent of loss, estimating and measuring the quantum of loss, commenting on underinsurance, recommending depreciation, taking expert opinion where required, and dealing with salvage.
The same regulatory framework requires neutrality and a code of conduct built around integrity, objectivity, impartiality, due diligence, proper technical standards and competent work.
Is the Surveyor’s Assessment Final and Binding?
No—but that answer needs an important qualification.
In New India Assurance Co. Ltd. v. Pradeep Kumar, the Supreme Court held that a surveyor’s report may form the foundation of settlement but is neither conclusive nor binding on the insurer or the insured.
The Supreme Court repeated that position in its 21 September 2026 judgment in New India Assurance v. Hemkund Duplex. But Hemkund also shows the danger of a vague challenge: where the insured merely complained that the reports were negative without identifying a specific professional or evidentiary deficiency, the Court criticised the forum for brushing the surveyor material aside.
So “the surveyor assessed too little” is a starting point, not an appeal ground. The stronger question is: what exactly was measured, excluded, depreciated, valued or assumed incorrectly?
If you do not yet have the complete survey report, photographs, calculations or other evidence relied on by the insurer, start with our survey-report and claim-file evidence guide before disputing the number.
Rebuild the Surveyor’s Assessment Before You Challenge It
Do not compare only your claim amount with the final survey figure. Reconstruct the path between them.
| Assessment component | Questions to ask |
| Quantity / extent of damage | What area, units, kilograms, tonnes, machines or stock lots were accepted? What was excluded? |
| Rate / unit cost | What rate per sq. ft., unit, kg, tonne or machine was used? What is the source and date of that rate? |
| Repair vs replacement | Did the surveyor assume repair where replacement was technically required, or replacement where repair was sufficient? |
| Valuation basis | Market value, reinstatement value, landed cost, manufacturing cost or another policy-defined basis? |
| Depreciation | What percentage, on which items, for what age/use and under which policy basis? |
| Salvage | What material was treated as recoverable, at what quantity and value, and who obtained the salvage quote? |
| Underinsurance / average | Was the value at risk correctly calculated and was the correct policy waiver/threshold used? |
| Excess / deductible | Was the correct policy excess applied once, or has a similar deduction effectively been duplicated? |
| Non-admissible items | Which items were excluded as uninsured or outside scope, and what clause was relied on? |
Once the assessment is broken into these parts, many disputes become much narrower. A ₹22 lakh gap may turn out to be ₹8 lakh of quantity dispute, ₹5 lakh of rate difference, ₹4 lakh of depreciation, ₹3 lakh of salvage and ₹2 lakh of underinsurance. Each piece needs different evidence.
1. Quantity and Scope: Was All the Damage Actually Counted?
Quantity errors are common where damage is spread across a large premises, stock is mixed with debris, machinery has multiple assemblies, or emergency repairs begin before the final survey.
For buildings, compare the surveyor’s measurements with drawings, BOQ, architect/engineer measurements and site photographs. For machinery, reconcile each affected component against the asset register, make/model and repair estimate. For stock, reconcile physical remnants, purchase records, stock ledger, production data and pre-loss declarations.
If the surveyor excluded an item, ask whether it was treated as undamaged, pre-existing damage, not insured, not present, unsupported, or outside the insured location. Those are different reasons and require different responses.
A claimant who simply submits a contractor’s lump-sum quotation gives the insurer very little to audit. A line-item BOQ linked to photographs and measurements is much harder to dismiss.
2. Rates: What Is the Basis for the Surveyor’s Price?
A low assessment may arise even where quantity is agreed because the surveyor uses lower labour, material, machinery or stock rates.
The right comparison is not always the claimant’s highest quotation against the surveyor’s lowest quotation. Look for like-for-like specifications, location, freight, taxes, installation, capacity, model equivalence and date of pricing.
| Weak evidence | Stronger evidence |
| One undated contractor estimate | Two or three dated itemised quotations with comparable scope |
| Quotation for upgraded machinery | Quotation for current equivalent capacity/specification |
| Retail price screenshot without freight/installation detail | Supplier quote showing base price, freight, duties, installation and commissioning |
| Generic construction rate | BOQ or engineer estimate tied to area, material grade and local rates |
| Claimant’s own stock price list | Invoices, landed-cost records, GST records and stock ledger |
If the surveyor uses a rate source that is materially below actual market evidence, ask for the source document or quotation relied on and its date. A rate without a traceable basis is much easier to challenge than a reasoned comparison of competing quotations.
3. Repair or Replace: The Technical Decision Can Drive the Entire Claim
A surveyor may assess a machine for repair while the OEM says the damaged assembly is unsafe or cannot be reliably restored. The opposite also happens: a claimant seeks full replacement where a technically sound repair would restore the property.
Do not make this an argument about preference. Obtain the OEM report, engineer opinion, test results, tolerance measurements, safety implications, spare-part availability and expected post-repair performance.
The regulations expressly contemplate expert opinion where required. If the disputed item involves specialised engineering, electrical systems, process equipment or structural safety, a reasoned technical opinion can be more persuasive than a general contractor quote.
4. Market Value vs Reinstatement Value: Check the Policy Before Accepting Depreciation
A large valuation gap can come from using the wrong settlement basis.
In M/s Oswal Plastic Industries v. Manager, Legal Deptt., N.A.I.C.O. Ltd. (2023), the Supreme Court restored the reinstatement-value amount because the relevant policy clause required that basis under the facts before it, rather than the lower depreciated value.
That does not mean every property claim is payable on a new-for-old basis. Some covers settle on market value, some on reinstatement value subject to conditions, and stock has its own valuation rules. The policy schedule, endorsements and operative clause decide the basis.
If the low assessment also includes a separate underinsurance deduction, audit that part independently using our Average Clause and underinsurance guide rather than mixing valuation and average into one objection.
5. Depreciation: Ask for the Percentage, Item and Reason
Depreciation should not appear as a mysterious percentage at the bottom of a spreadsheet.
The Surveyors and Loss Assessors Regulations specifically contemplate the surveyor recommending whether depreciation applies and the percentage and quantum of depreciation. That makes the working auditable.
Ask: which item has been depreciated; what age and condition were assumed; what percentage was used; whether the policy settlement basis permits that depreciation; and whether the same ageing effect has already been built into the rate or valuation.
Watch for double counting. For example, using a second-hand market-value rate and then deducting a second layer of age depreciation may require explanation. Whether it is wrong depends on the valuation model and policy, but it should be transparent.
6. Salvage: A High Salvage Deduction Can Quietly Reduce the Claim
Damaged property may still have scrap or resale value. That can legitimately affect the settlement, but the quantity and price should be supportable.
Ask for the salvage inventory, photographs, weight/quantity, bidder quotations and whether taxes, lifting, segregation and transport costs were considered where relevant.
If the insurer assumes a high salvage value but leaves the damaged material with the insured, the claimant should understand exactly how the deduction and salvage ownership interact under the settlement.
A speculative salvage number is not the same as an actual market offer. Conversely, the claimant cannot treat obviously recoverable metal, machinery components or stock as valueless merely because the main property is damaged.
7. Stock Loss: The Survey Often Becomes an Accounting Reconstruction
Fire-damaged stock claims are difficult because the physical evidence may be partly destroyed. The surveyor may have to reconstruct quantity and value using stock registers, purchase invoices, production records, GST data, bank stock statements, dispatch records and remnants at site.
The Supreme Court’s Khatema Fibres decision is a caution for claimants relying on inconsistent records. There, the surveyor used a scientific/volumetric method after examining the available material, and the Court declined to replace that assessment merely because the insured claimed a much larger stock loss.
The lesson is not that surveyors always win stock disputes. It is that a claimant needs to show why the chosen methodology is unreliable or why better contemporaneous evidence produces a different result.
| Record | What it should help prove |
| Opening stock and purchase invoices | What stock entered the business |
| Production / consumption records | What was used or converted before the loss |
| Sales / dispatch / GST records | What had left the premises |
| Bank stock statements | What the business declared before the loss |
| Physical remnants / weighment | What remained after the incident |
| Audited accounts | Whether broader inventory numbers are consistent |
| Insurance declarations | What quantity/value had been represented to the insurer before the claim |
Can You Demand a Second Surveyor?
You can ask the insurer to review the assessment, obtain clarification, seek re-inspection, or consider another expert/surveyor—but there is no automatic right to a second survey simply because the first number is unsatisfactory.
In Sri Venkateswara Syndicate v. Oriental Insurance (2009), the Supreme Court held that an insurer cannot keep appointing surveyors one after another merely to obtain a convenient report. A second surveyor is not prohibited, but cogent reasons are required for rejecting the first report and appointing another.
The same principle cuts both ways. If you want the insurer to depart from the first assessment, identify the inherent defect: wrong measurements, missing assets, unsupported rates, wrong policy basis, arithmetic error, ignored documents, technical issue requiring expert opinion, or another concrete deficiency.
Often the better first request is not “appoint a new surveyor.” It is “please obtain a reasoned addendum/review addressing these eight identified errors and the attached evidence.”
What the September 2026 Supreme Court Decision Changes—or Does Not Change
New India Assurance v. Hemkund Duplex, decided on 21 September 2026, does not create a new rule that surveyor reports are untouchable. The Court expressly revisited Pradeep Kumar, Khatema Fibres and Sri Venkateswara Syndicate and reaffirmed the established framework.
The practical message is sharper: surveyor reports are important statutory evidence; they are not conclusive; a surveyor is governed by a professional code; and a party challenging the report should identify a real deficiency rather than asking a forum to disregard expert material on a bare assertion.
For claimants, this makes the quality of the objection more important. A spreadsheet showing the surveyor’s line item, your competing figure, the exact reason for disagreement and the supporting document is far stronger than a three-page letter saying the assessment is arbitrary.
When a Low-Assessment Challenge Is Stronger
The surveyor’s measurements conflict with site drawings, photographs, joint measurements or an engineer’s signed measurement sheet.
A repair rate is materially below multiple like-for-like market quotations and the survey report gives no source for the adopted rate.
The surveyor assumes repairability despite an OEM/engineer report explaining why safe or functional restoration is not technically possible.
Depreciation is applied even though the operative policy basis requires reinstatement value under the facts and conditions of the claim.
The salvage deduction has no inventory, bidder quote, quantity or market basis.
Stock quantity is rejected despite reconciled pre-loss records that are consistent across purchase, production, GST, bank and dispatch data.
Documents submitted before the final report are not addressed, or the report says “not provided” despite proof of submission.
The surveyor used a valuation method outside the relevant licensed competence without obtaining appropriate technical assistance, or the calculation contains identifiable arithmetic/duplication errors.
When the Challenge May Be Difficult
The objection is only that the claimed amount was higher than the survey amount.
The claimant relies on quotations prepared after the loss that do not match the damaged property’s specification, capacity or scope.
Stock records materially conflict with GST, bank stock statements, purchases, production or dispatch records and no credible reconciliation is offered.
The policy settles on market value but the claimant demands new replacement cost without satisfying a reinstatement-value clause or endorsement.
The surveyor’s report explains the methodology, uses traceable documents and measurements, answers the claimant’s submissions and contains no obvious technical or contractual defect.
The claimant requests a second surveyor without first identifying why the original assessment is defective.
Documents to Assemble Before Challenging the Assessment
| Document / evidence | Purpose |
| Full policy schedule, wording and endorsements | Identify settlement basis, excess, average and special clauses. |
| Final survey report plus annexures/workings | See the exact accepted quantities, rates and deductions. |
| Spot survey / preliminary report if available | Compare early observations with the final scope. |
| Photographs and videos from immediately after loss | Prove extent and condition before debris removal/repairs. |
| Joint measurement sheets / site drawings / BOQ | Challenge quantity and scope. |
| OEM / engineer / architect report | Challenge repairability, structural safety or technical method. |
| Dated itemised quotations | Challenge adopted rates on a like-for-like basis. |
| Fixed asset register and original invoices | Identify property, specifications, age and ownership. |
| Stock ledger, purchase, production, GST and dispatch records | Reconstruct quantity/value of damaged stock. |
| Salvage bids / weighment / inventory | Test salvage deduction. |
| Emails and document-submission acknowledgements | Prove what the surveyor had before finalising the report. |
| Your line-by-line counter-calculation | Show exactly how the corrected amount is derived. |
If the surveyor is still raising repeated document queries, organise the response using our claim query and deficiency-letter guide so every submission is dated and traceable.
Use a Line-by-Line Dispute Matrix
| Surveyor item | Surveyor figure | Your figure | Why different | Evidence |
| Roof sheeting quantity | 4,000 sq. ft. | 5,450 sq. ft. | Survey omitted rear bay | Architect measurement + photos |
| Replacement rate | ₹X / sq. ft. | ₹Y / sq. ft. | Survey rate predates loss / different grade | 3 dated supplier quotes |
| Machine repair | Repair allowed | Replacement required | OEM says core assembly unsafe | OEM failure report |
| Depreciation | 20% | 0% / lower | Disputed under policy settlement basis | Policy clause + asset evidence |
| Salvage | ₹4.5 lakh | ₹2.1 lakh | No buyer at adopted value | 3 salvage bids + weighment |
This format forces the insurer to respond to actual points. It also prevents the appeal from becoming a second, larger claim with no bridge back to the surveyor’s assessment.
How to Appeal a Low Surveyor Assessment
First, obtain the final report and calculation. Second, mark every disputed line item. Third, attach evidence that uses the same measurement or valuation unit. Fourth, ask the insurer for a reasoned review or surveyor addendum.
Do not allege bias merely because the number is low. If there is a genuine neutrality, competence or code-of-conduct issue, state the facts precisely: conflict of interest, refusal to inspect a material area, ignored technical evidence, work outside competence, unexplained methodology or another identifiable breach.
Ask the insurer to state whether it accepts the surveyor’s methodology and, if so, why your contrary evidence does not change the assessment. The insurer remains responsible for its claim decision; it should not hide behind the sentence “as per surveyor report.”
If the dispute also involves average, excess, policy exclusion or business interruption, separate those modules. One clear representation with distinct headings is better than mixing five different calculations together.
Where the property assessment is also affecting a consequential-loss claim, keep the financial-loss calculation separate and use our Business Interruption / Loss of Profit guide for the BI component.
Do Not Let a Low Assessment Become a Full-and-Final Settlement by Accident
If the insurer offers the survey amount against a discharge voucher, understand whether the payment is being offered on account, undisputed, or in full and final settlement.
If you dispute the quantity or valuation, record the objection before signing any document that may later be relied on as acceptance of the settlement. Whether a discharge can be challenged later depends on the facts and evidence; an after-the-event objection is usually harder.
Before signing a disputed settlement, review our full-and-final discharge voucher guide and preserve your counter-calculation in writing.
When to Escalate Beyond the Insurer
Escalation makes more sense after the technical dispute has been crystallised. A grievance authority cannot efficiently evaluate “the surveyor paid too little” if the claimant has never identified the disputed measurements, rates or clauses.
Submit the line-by-line matrix to the insurer’s grievance mechanism first and ask for a reasoned reply. If the dispute remains unresolved, the next route depends on the claimant, amount, policy, nature of dispute and forum jurisdiction.
For a practical comparison of grievance routes, see our Bima Bharosa vs Insurance Ombudsman guide before selecting the escalation channel.
What the Key Supreme Court Decisions Mean for a Claimant
| Decision | Practical lesson |
| New India Assurance v. Pradeep Kumar (2009) | Surveyor report is important but not conclusive or binding on insurer/insured. |
| Sri Venkateswara Syndicate v. Oriental Insurance (2009) | Second surveyor is not a routine do-over; cogent reasons are needed to reject the first report. |
| Khatema Fibres v. New India Assurance (2021) | A forum will not simply re-do a sound technical assessment; identify code-of-conduct, methodology or arbitrary-decision defects. |
| M/s Oswal Plastic Industries v. N.A.I.C.O. (2023) | The policy’s valuation basis matters; reinstatement value prevailed under that clause/facts instead of depreciated value. |
| New India Assurance v. Hemkund Duplex (Supreme Court, 21 Sep 2026) | Reaffirmed that surveyor reports are not conclusive, but a party challenging them should point to specific deficiency rather than rely on a bald disagreement. |
These cases are not a formula for getting a higher claim. Together they create a discipline: respect the surveyor’s expert role, but test the report against the policy, regulations, evidence and its own methodology.
How Tatkal Claims Can Help
Tatkal Claims can review the policy wording, final survey report, measurement sheets, valuation basis, depreciation, salvage, stock reconciliation, underinsurance working and claimant quotations to isolate where the assessment may be technically or contractually unsupported.
Where there is a documented issue, assistance can include preparing a line-by-line counter-assessment, organising supporting records, framing a focused representation to the insurer and escalating an unresolved dispute through the appropriate grievance route. A higher settlement cannot be promised: a reasoned survey assessment supported by the policy and reliable evidence may remain difficult to displace.
Frequently Asked Questions
Frequently asked questions
Is the insurance surveyor’s report final and binding?
No. Supreme Court decisions have repeatedly said a surveyor’s report is important evidence and may form the foundation of settlement, but it is not conclusive or automatically binding on the insurer or insured. A challenge should identify specific defects in the assessment.
Can I reject the surveyor’s amount just because my contractor estimate is higher?
You can dispute it, but a higher contractor estimate alone may not be enough. Compare quantity, specification, rate source, repair scope, valuation basis, depreciation and salvage on a like-for-like basis and explain each difference.
Can I ask the insurer to appoint a second surveyor?
You can request review, re-inspection or another surveyor, but a second surveyor is not an automatic right. Supreme Court authority says another surveyor should not be appointed merely as a routine do-over; there should be cogent reasons for departing from the first report.
What if the surveyor has used very low repair rates?
Ask for the source and date of the adopted rates and submit like-for-like quotations covering the same specification, location, freight, taxes, installation and labour scope. The stronger dispute is about methodology and comparability, not simply a higher price.
Can a surveyor apply depreciation to machinery or building repairs?
Potentially, depending on the policy settlement basis and item. The regulations contemplate the surveyor recommending the applicability, percentage and quantum of depreciation. Ask for the exact percentage, item and policy/valuation basis.
What if my policy is on reinstatement value but the surveyor paid depreciated value?
Check the exact reinstatement-value clause and whether its conditions were satisfied. In Oswal Plastic Industries, the Supreme Court required reinstatement value under the wording and facts before it. That result should not be assumed for a different policy without reading its clause.
How do I challenge a high salvage deduction?
Ask for the salvage inventory, quantity/weight, photographs, bidder quotations and price basis. Compare those figures with actual market bids and clarify who retains or disposes of the salvage under the settlement.
What evidence is strongest in a stock-loss dispute?
Consistent contemporaneous records: purchase invoices, opening stock, production/consumption, GST/sales/dispatch records, bank stock statements, insurance declarations and physical remnants. The records should reconcile rather than merely point to one large closing-stock number.
Can the insurer simply say 'as per surveyor report' and refuse to discuss my evidence?
The insurer can rely heavily on the survey report, but a focused grievance should ask it to address the specific contrary evidence and disputed methodology. The claim decision remains the insurer’s responsibility; the survey report is not automatically conclusive.
What is the best format for challenging a low property assessment?
A line-by-line matrix works well: surveyor item, surveyor figure, your figure, exact reason for difference, policy/technical basis and supporting evidence. It turns a general complaint into an auditable valuation dispute.
Sources and Methodology
Disclaimer: This guide explains property-loss survey assessment disputes in India in general terms. Whether a surveyor’s assessment is sustainable depends on the policy wording, insured item, settlement basis, measurements, technical evidence, stock records, depreciation, salvage, underinsurance, excess and the facts of the loss. A low assessment is not automatically wrong, and the cases cited do not guarantee a higher settlement. This is not legal, engineering, valuation or loss-adjusting advice for a specific claim.