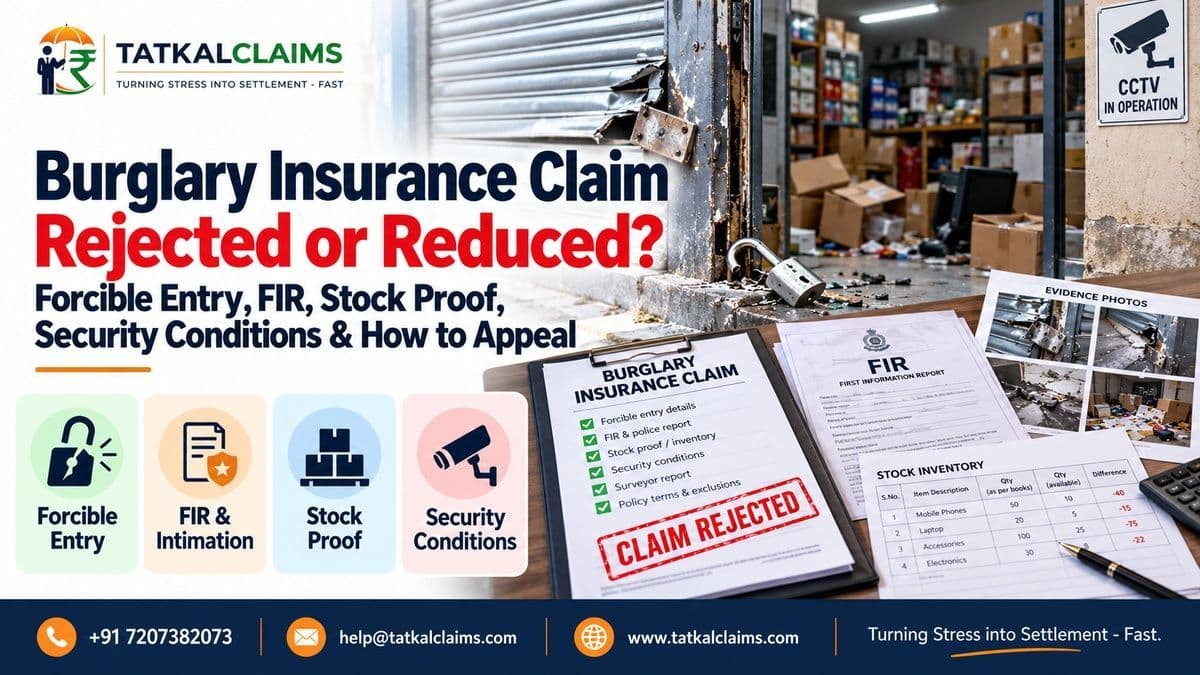
The shutters are open when they should not be. A lock is missing, a rear door has been tampered with, or cartons that were there the previous evening are gone. The police are called, stock is counted, CCTV is checked—and then the insurer asks a question that feels strangely narrow: “Where is the evidence of forcible and violent entry?”
That question matters because many commercial burglary policies in India do not cover every theft. Their base wording can require theft to follow an actual forcible and violent entry into or exit from the insured premises. At the same time, some policies offer broader theft extensions, so the answer cannot be guessed from the word “burglary” on the schedule alone.
The practical job is to separate three issues: was the event covered under this exact policy, can the manner of entry or exit be proved, and can the stolen property and amount be proved. A claim can be strong on one and weak on another.
What a Commercial Burglary Policy Usually Covers
A current commercial burglary wording from Tata AIG covers scheduled property lost, destroyed or damaged by burglary or housebreaking defined as theft following an actual forcible and violent entry into or exit from the premises, as well as hold-up. It also covers certain damage to the insured premises caused by such entry, exit or an attempt.
HDFC ERGO’s current burglary product page describes the same broad base structure: contents, stocks and goods can be insured against burglary/housebreaking involving actual forcible and violent entry or exit, with hold-up risk and damage to premises. It also lists a separate theft extension.
That difference is crucial. If your schedule includes a theft extension or broader package wording, the absence of a broken shutter may not automatically decide the claim. If your policy only has the classic burglary wording, the manner of entry or exit can become decisive.
Why “Forcible and Violent Entry” Matters
The Supreme Court’s decision in United India Insurance Co. Ltd. v. Harchand Rai Chandan Lal remains the leading authority for classic burglary wording. The Court held that where the policy defines burglary by reference to forcible and violent entry or exit, that requirement must be proved; a court cannot rewrite the contract into a general theft policy.
The practical meaning is more nuanced than “there must be a smashed door.” Judicial decisions applying this wording have distinguished between mere use of a key and entry involving picking or forcing a lock. Evidence of bending a shutter, broken locking points, prised doors, forced catches, damaged grills or violent exit can matter.
A 2026 Madhya Pradesh High Court decision, National Agencies v. SBI General, applied the same principle where the allegation was that duplicate keys had been used and no forcible entry or exit was demonstrated. The Court treated the claim as outside that particular policy wording.
That does not create a universal rule that duplicate-key theft is never insured. A separate theft extension, fidelity cover, key extension, hold-up wording or other endorsement can change the result. The schedule controls.
What Evidence Can Prove Forced Entry or Exit?
| Evidence | Why it matters |
| Photographs/video before repairs | Shows broken locks, shutter distortion, tool marks, damaged grill, forced latch, broken glass or exit damage. |
| Police spot panchnama / scene record | Independent contemporaneous description of the premises. |
| CCTV footage | May show forced entry, route of access, number of persons, timing or use of tools. |
| Broken lock / latch / shutter parts | Physical evidence can support the mechanism of entry. |
| Security guard statement | Helps establish closing condition, discovery, alarm events and suspicious movement. |
| Locksmith / engineer note | Can explain whether a lock was picked, forced, cut or opened normally. |
| Alarm/access-control logs | Can show forced door event, code usage or abnormal access. |
| Surveyor photographs and site notes | Important if repairs started before the insured took complete photographs. |
Do not repair the entry point before it is documented unless safety requires immediate action. If emergency repair is unavoidable, photograph and video the damage first, preserve removed locks or hardware, and keep the repair invoice.
A police FIR is important, but the FIR section number by itself does not decide insurance cover. What matters is the actual policy wording plus the factual evidence of entry, exit, assault, threat or other covered mechanism.
What If the Thief Used a Key?
This is a frequent rejection scenario. Classic burglary wording can fail where entry occurred using an original or duplicate key without force or violence.
Bharat Watch Company v. National Insurance reached the Supreme Court after a theft where the surveyor found no sign of forcible entry and duplicate keys were suspected. The Court did not dilute Harchand Rai’s interpretation of forcible-entry wording. Instead, it allowed that insured’s appeal because lower fora had concurrently found that the exclusionary/special conditions relied on by the insurer had not been supplied to the insured.
So there are two separate questions: what the clause means, and whether that clause was actually part of the contract communicated to the insured. Do not confuse them.
If keys were stolen from an employee or owner through assault or threat, check whether the policy has specific safe/key/hold-up wording. If an employee simply used authorised access to steal stock, the problem may belong under fidelity/employee-dishonesty cover rather than ordinary burglary cover.
Employee, Insider or Lawful-Person Theft: A Different Risk
Current commercial burglary wording commonly excludes loss where a member of the insured’s household, business staff or another person lawfully on the premises was concerned in or assisted the theft.
That means an insurer may investigate whether the event was an outside burglary or an internal disappearance. CCTV, access logs, attendance, key registers, stock movement and police investigation can become more important than physical damage alone.
If employee dishonesty is a genuine possibility, check whether the business had Fidelity Guarantee or another employee-dishonesty cover. Do not try to force an insider-theft fact pattern into a burglary clause that expressly excludes it.
FIR, Police Intimation and the First 24 Hours
Some current burglary wordings require the insured to notify both the police and insurer forthwith and submit a written claim with particulars within a stated period. Tata AIG’s current commercial wording, for example, requires immediate written notice to police and insurer and a written claim within seven days after the loss becomes known.
Your own policy may use different wording, so do not copy a seven-day rule blindly. The safe practice is immediate police and insurer intimation, followed by a detailed written inventory as soon as it can be prepared accurately.
| Action | Practical reason |
| Call police and obtain diary/FIR details | Creates a contemporaneous crime record. |
| Notify insurer/TPA/claim desk in writing | Creates claim timestamp and preserves survey rights. |
| Do not disturb entry point unnecessarily | Protects evidence of force or route of access. |
| Photograph every access point | Insurer may later dispute whether entry was forced. |
| Preserve CCTV and alarm backups | Systems can overwrite footage quickly. |
| Freeze stock movement temporarily | Prevents post-loss inventory confusion. |
| Prepare preliminary missing-stock list | Useful for police, surveyor and internal controls. |
| Keep broken locks/hardware | Can support forced-entry mechanism. |
A late FIR or delayed insurer notice does not have the same consequence under every wording and every fact pattern. But delay makes proof harder: the scene changes, CCTV is overwritten, employees forget detail, and the insurer may argue prejudice or breach of a condition.
Proving That Stock Was Actually Stolen
Many burglary claims fail or shrink after coverage is accepted because the missing stock cannot be reconciled.
A current commercial burglary wording can require complete books, accounts and stock records. The insurer may ask for purchase invoices, sales and dispatch records, GST data, stock ledgers, production records, bank stock statements and prior insurance declarations.
The strongest stock claim does not begin with a round figure written after the theft. It begins with a reconciliation that can be independently followed from opening stock to purchases, production, sales/dispatch and physical closing balance.
| Record | What it helps establish |
| Opening inventory | Starting quantity/value before the loss period. |
| Purchase invoices / inward register | Goods received before the burglary. |
| Production / conversion records | Raw material consumed and finished goods created. |
| Sales / GST / dispatch records | Goods that legitimately left before the burglary. |
| Bank stock statements | What the business had represented to its lender before the loss. |
| Physical post-loss count | What remained after the burglary. |
| Police seizure/recovery records | Any goods later recovered. |
| Surveyor inventory | What the insurer actually accepted as missing. |
If different records do not match, explain the reconciliation before the insurer finds the inconsistency. A credible adjustment note is better than pretending all systems always show identical numbers.
Security Conditions, Alarms, Watchmen and Keys
Burglary underwriting is highly dependent on premises security. Current wordings can make agreed protections a condition precedent to liability, require keys to be removed when premises are unattended, require alarm codes to remain secret, and require reasonable precautions with locks, bolts and fastenings.
Proposal forms also commonly ask whether there is a watchman, whether premises are ever left unoccupied, how valuables are stored, how many keys exist and whether stock books are maintained.
This is why a claim can become difficult when the proposal said “24-hour guard + functioning alarm” but the guard post was vacant or the alarm had been disconnected for months.
Do not assume every security breach automatically defeats the claim. Read whether the requirement is a warranty, condition precedent, material representation or ordinary precaution clause, and whether the insurer can show the breach actually engages the policy wording.
But if the policy explicitly makes a safeguard a condition precedent, ignoring it is a serious problem. Preserve service logs, alarm reports, guard rosters and key-control records before the insurer asks.
What If the Premises Were Closed or Unoccupied for Several Days?
Some burglary policies suspend or cease cover after a specified period of continuous unoccupancy unless the insurer has agreed otherwise. Tata AIG’s current commercial wording, for example, says cover ceases to attach if the premises are left uninhabited day and night for seven or more consecutive days and nights.
Do not generalise that exact period to another insurer or product. Check your own vacancy/unoccupancy clause and any endorsement for seasonal closure, holidays, renovation or temporary shutdown.
Evidence of occupancy can include employee attendance, electricity consumption, security logs, delivery records, CCTV, alarm events and business transactions.
No Broken Lock? Check for a Theft Extension Before Accepting Rejection
This is one of the most important checks in a modern claim. HDFC ERGO’s current burglary product information lists “Theft” as an extension in addition to the classic burglary/housebreaking cover.
If your schedule shows a theft extension, read its wording before accepting a rejection based only on absence of visible forced entry. The extension may have its own exclusions, excess, sub-limit, first-loss basis or security requirements.
Likewise, a business package can combine burglary with different ancillary covers. The correct question is not “What does burglary usually mean?” but “What exactly did this insured buy?”
When Coverage Is Accepted but the Surveyor Cuts the Amount
Once the insurer accepts that a covered burglary occurred, the dispute can move from coverage to quantum. The surveyor may reduce the claim for unsupported stock, underinsurance, first-loss limits, depreciation on contents, excess, recovered goods or valuation basis.
If the event is accepted but the surveyor’s quantity or valuation is too low, use our Low Surveyor Property Assessment guide to challenge the assessment line by line.
Keep the issues separate. “There was forcible entry” does not prove ₹30 lakh of stock was stolen, and a perfect stock reconciliation does not cure a policy that excludes the manner of entry.
Underinsurance and First-Loss Structures
Some burglary covers are written on full-value basis; others can use first-loss structures. Current commercial wordings may also contain an average/underinsurance condition.
If the value of property at risk exceeded the relevant sum insured, the insurer may apply a proportionate reduction depending on the wording. If the policy uses a first-loss basis, the arithmetic can be different again.
Where the settlement includes an average/underinsurance deduction, audit that calculation separately using our Average Clause guide and the burglary policy’s own condition.
Do not assume the 85% waiver used in some standard fire products applies to a standalone burglary policy. It may not.
What Happens if Police Recover Some of the Stolen Property?
Recovery does not erase the burglary, but it can affect quantum. Keep police seizure memos, release orders, photographs and evidence of the condition of recovered goods.
Recovered stock may be damaged, obsolete, incomplete or unsaleable. The insurer should not simply treat every recovered item as full-value recovery without considering condition and policy valuation.
The policy may also give the insurer subrogation rights after payment, so cooperate with reasonable recovery and prosecution steps required by the wording.
When a Burglary Rejection Is More Open to Challenge
The insurer says there was no forced entry, but contemporaneous police records, photographs, CCTV or survey notes show broken locks, forced shutters, damaged catches or violent exit.
The insurer relies on classic burglary wording even though the schedule contains a separate theft extension or broader endorsement.
The repudiation relies on a special exclusion/condition that the insured can credibly show was never supplied or communicated, subject to the evidence and Bharat Watch principles.
The insurer says stock was not proved, but purchase, sales, GST, bank and physical records reconcile consistently.
The surveyor accepts the event but applies a stock quantity, value, underinsurance percentage or deduction that is not supported by the underlying records.
The insurer characterises the theft as employee-assisted without evidence connecting staff or another lawful entrant to the loss.
When the Claim May Be Difficult to Improve
The base policy requires forcible and violent entry/exit, no theft extension exists, and the evidence shows normal key access with no force, threat or covered hold-up.
The police complaint, insured statement, CCTV and surveyor version materially conflict on how the premises were entered.
The proposal promised safeguards that were expressly conditions precedent, but those safeguards were knowingly not in operation at the time of loss.
The missing stock cannot be reconciled and pre-loss books contain major unexplained inconsistencies.
Evidence points to an employee or another lawful person participating in the theft and the burglary wording excludes such involvement.
The premises were continuously unoccupied beyond a policy limit without required insurer consent, where the clause clearly suspends cover.
Documents to Collect Before Appealing
| Document | Purpose |
| Policy schedule + full wording + endorsements | Establish exact burglary/theft/hold-up cover and exclusions. |
| Proposal form | Check declared security, occupancy, watchman, alarm and key controls. |
| FIR / police diary / panchnama / final report | Prove contemporaneous event and police findings. |
| Scene photographs and CCTV | Prove route and mechanism of entry/exit. |
| Survey report and site photographs | See what insurer accepted or disputed. |
| Broken locks / locksmith report | Support forced-entry mechanism. |
| Alarm/access-control logs | Support timing and manner of entry. |
| Guard roster / statements | Prove occupancy and security operation. |
| Stock ledger + purchase + GST + sales/dispatch | Prove quantity of missing stock. |
| Bank stock statements | Cross-check pre-loss declarations. |
| Recovered-property records | Adjust quantity and condition properly. |
| Repudiation / settlement letter | Identify the exact contractual ground being used. |
If the insurer has not shared the survey report or evidence relied on for repudiation, use our claim-file and survey-report evidence guide before drafting the appeal.
Questions to Put to the Insurer in Writing
| 1 | What exact operative clause or exclusion is relied on? |
| 2 | Does the schedule contain any theft, hold-up, key, fidelity or other extension relevant to the event? |
| 3 | What evidence leads the insurer to conclude there was no forcible or violent entry/exit? |
| 4 | Which police, surveyor, CCTV or scene evidence was considered? |
| 5 | If staff involvement is alleged, what evidence links the staff member to the theft? |
| 6 | Which stock items and quantities were accepted as missing and which were rejected? |
| 7 | What valuation basis, excess, first-loss limit or underinsurance calculation has been applied? |
| 8 | If a security condition is relied on, where is it shown in the policy and what breach is alleged? |
| 9 | If delayed notice is relied on, what exact notice condition applies and what prejudice is said to have resulted? |
| 10 | Please provide the surveyor report, annexures, photographs and calculation sheets relied on. |
How to Appeal a Burglary Claim Rejection
Start with the insurer’s exact rejection sentence. Do not send a general letter saying “burglary clearly happened.” Put the wording and evidence next to each other.
If the issue is force, attach scene evidence. If it is stock, attach a reconciliation. If it is a security breach, attach alarm/guard/key records. If it is insider involvement, address the factual basis. If it is a theft extension, put the endorsement on the first page of the representation.
Where the insurer raises repeated document queries, respond in a dated index rather than sending scattered attachments.
For that document-control process, use our claim query and deficiency-letter guide so the insurer cannot easily say a crucial record was never supplied.
Ask for a reasoned review that addresses each contractual and factual point. A useful grievance is built around the policy language—not around anger at the theft or the insurer.
Be Careful With a Short-Settled Burglary Claim
If the insurer accepts burglary but offers a reduced amount, find out whether the payment is an on-account/undisputed amount or a full-and-final settlement.
Before signing a disputed voucher, review our full-and-final discharge voucher guide and preserve your stock/valuation objection in writing.
Coverage and quantum can be disputed simultaneously, but keep them as separate headings. That makes later review much easier.
When to Escalate Beyond the Insurer
Escalate after the dispute has been crystallised: clause, evidence, amount and the response you want. A grievance forum cannot efficiently decide a complaint that only says “theft occurred but insurer is refusing.”
For escalation choices, use our Bima Bharosa vs Insurance Ombudsman guide and check the current forum eligibility, monetary limits and policyholder status before filing.
Commercial-policy disputes can involve forum-jurisdiction and maintainability questions, so do not assume every business claimant has the same grievance route as an individual retail policyholder.
Key Indian Decisions to Understand
| Decision | Practical point |
| United India Insurance v. Harchand Rai Chandan Lal, Supreme Court (2004) | Where policy defines burglary through forcible and violent entry/exit, courts apply that contractual requirement. |
| Bharat Watch Company v. National Insurance, Supreme Court (2019) | Harchand Rai remains valid, but an insurer may face difficulty relying on exclusionary/special conditions that were found not to have been supplied to the insured. |
| National Agencies v. SBI General, Madhya Pradesh High Court (2026) | Recent application of classic wording: alleged duplicate-key entry without demonstrated force/violence did not satisfy that burglary clause. |
| Surya Roshni v. United India Insurance, NCDRC (2024) | Reiterated that where the wording requires forcible and violent entry, the nature and timing of force in relation to entry/exit matter. |
These decisions are not substitutes for the schedule in your hand. A theft extension, package wording, safe/key clause or fidelity cover can produce a different result.
How Tatkal Claims Can Help
Tatkal Claims can review the burglary wording, schedule and extensions, police papers, survey report, CCTV/scene evidence, security records and stock reconciliation to identify whether the rejection is really about coverage, proof of entry, stock quantum, security conditions or underinsurance.
Where there is a documented basis to challenge the decision, assistance can include preparing a clause-by-clause representation, organising crime-scene and stock evidence, responding to surveyor queries and escalating the unresolved claim through an appropriate grievance route. We cannot promise payment: if the event genuinely falls outside the purchased wording, the rejection may be contractually sustainable.
Frequently Asked Questions
Frequently asked questions
Does burglary insurance cover every theft from a shop or warehouse?
Not necessarily. Many base burglary policies require theft following actual forcible and violent entry or exit. Some policies add a broader theft extension. Check the schedule, wording and endorsements rather than assuming every theft is covered.
Is a broken lock compulsory for a burglary claim?
Not in every policy or fact pattern. What matters is the wording and evidence of the required force/violence or other covered mechanism. Tool marks, forced catches, damaged shutters or violent exit may be relevant even if a particular lock is missing. A theft extension can also change the analysis.
What if thieves entered using a duplicate key?
Under classic burglary wording requiring forcible and violent entry/exit, ordinary key access without force can be outside cover. But check for theft, key, hold-up or other extensions before accepting a rejection.
Do I need an FIR for a burglary insurance claim?
Police intimation is usually critical and many wordings require prompt notice to police and insurer. The exact contractual requirement varies. An FIR/police record also preserves contemporaneous evidence about entry, missing property and investigation.
Can the insurer reject because there were no visible break-in marks?
Potentially, if the policy specifically requires forcible/violent entry and the available evidence cannot establish it. But first check the full scene evidence and whether a broader theft extension applies. Absence of one visible mark is not the same as proving normal entry.
Is employee theft covered under burglary insurance?
Often not under classic burglary wording; current commercial policies can exclude theft involving business staff or another person lawfully on the premises. Fidelity Guarantee or employee-dishonesty cover may be more relevant, depending on the policy portfolio.
How do I prove the quantity of stock stolen?
Reconcile opening stock, purchases, production/consumption, sales/dispatch/GST records and the post-loss physical count. Bank stock statements and prior insurance declarations can provide additional cross-checks.
Can a non-working alarm or absent watchman cause rejection?
It can be serious if the policy or proposal made that safeguard a condition precedent or material basis of cover. The exact clause and facts matter. Preserve alarm service records, guard rosters and any insurer-approved changes.
What if my premises were closed for a long holiday?
Check the unoccupancy/vacancy clause. Some burglary policies suspend cover after a stated number of continuously unoccupied days unless the insurer agrees otherwise. The period differs by policy, so use your actual wording.
What is the strongest way to appeal a burglary rejection?
Match each rejection ground to the contract and evidence: policy clause or extension, physical/police proof of entry, security records, stock reconciliation, surveyor working and any underinsurance calculation. A clause-by-clause appeal is stronger than a general statement that a theft occurred.
Sources and Methodology
Disclaimer: This guide explains commercial burglary insurance claim disputes in India in general terms. Burglary, theft, housebreaking, hold-up, key use, employee involvement, security warranties, unoccupancy, stock valuation, first-loss cover and underinsurance depend on the exact schedule, wording and endorsements. The cited court decisions are fact- and clause-specific. This is not legal, security, accounting or loss-adjusting advice for a particular claim.