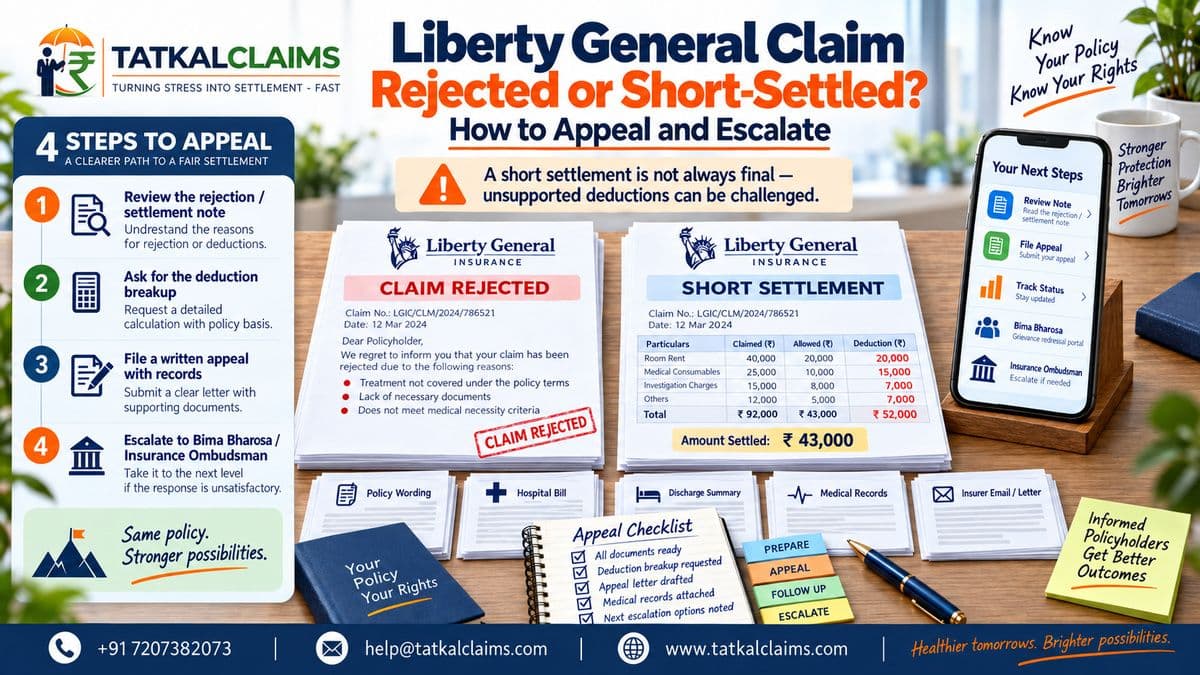
If Liberty General Insurance Limited has rejected your insurance claim, reduced the amount payable, delayed settlement or denied a cashless request, you do not necessarily have to accept the first decision as final.
The right response depends on why Liberty rejected or reduced the claim. A useful appeal should identify the exact policy clause, medical conclusion, survey finding, documentation issue or deduction relied upon by the insurer and answer that specific point with evidence.
Liberty currently publishes a multi-stage grievance ladder beginning with customer care and progressing through managerial escalation, the Grievance Redressal Officer and the Chief Grievance Redressal Officer.
First: Identify What Happened to Your Liberty General Claim
| Claim problem | What to obtain | What your appeal should examine |
|---|---|---|
| Claim rejected completely | Repudiation/rejection letter | Exact exclusion, warranty, condition or factual basis |
| Claim short-settled | Settlement sheet and deduction calculation | Every deduction and its policy basis |
| Cashless request denied | Pre-authorisation response or denial | Whether cashless was denied or the underlying claim itself was rejected |
| Reimbursement delayed | Claim acknowledgement and document trail | Date complete documents were received and any outstanding requirements |
| PED/non-disclosure rejection | Proposal form and medical records | What was asked, what was disclosed and whether the alleged fact was material |
| Motor claim reduced | Survey assessment and repair estimate | Depreciation, causation, excluded damage, salvage and repair valuation |
| Theft claim delayed | FIR, no-trace report and insurer correspondence | Documentation and theft-claim compliance |
| Total-loss dispute | Survey report, IDV and repair estimate | Repair economics, IDV, salvage and policy conditions |
For the broader principles that apply across insurers, use Tatkal Claims' Insurance Claim Rejected? What to Do Next – Complete Guide for India alongside this Liberty-specific guide.
Liberty General's Claim Numbers Need Context
Nyvo's 2026 comparison, based on published IRDAI data and calculated as a three-year weighted average, lists Liberty General at a 90.0% claim settlement ratio and 15 complaints per 10,000 claims.
These figures are company-level indicators. They do not tell you whether your specific claim should be accepted or rejected and should therefore be treated as context rather than a prediction about an individual claim.
Step 1: Obtain the Exact Rejection or Deduction Reason
Start with Liberty's written decision. If the claim has been rejected, identify the policy clause relied upon, the factual or medical conclusion relied upon, the document the insurer says is missing, any alleged non-disclosure or breach, and the date and reasoning in the repudiation communication.
For a short-settled claim, request a complete calculation showing how Liberty moved from the amount claimed to the amount actually paid. A settlement figure without a clear calculation is difficult to challenge effectively.
Your appeal should deal with each disputed deduction separately rather than asking Liberty generally to reconsider the claim.
Step 2: Register the Complaint With Liberty General
Liberty's current first-level grievance channels include toll-free number 1800-266-5844, available from 8:00 AM to 8:00 PM seven days a week, and email care@libertyinsurance.in.
Liberty also publishes its customer-service postal address at One International Center, Prabhadevi, Mumbai.
For senior citizens, Liberty publishes seniorcitizen@libertyinsurance.in.
Your complaint should state the policy number, claim number, date of loss or hospitalisation, amount claimed, amount rejected or deducted, precise decision being challenged, policy clause in dispute, evidence supporting your position and exact remedy requested.
Keep the acknowledgement or complaint reference.
Step 3: Escalate to Liberty's Manager Level
If Liberty's first response does not resolve the dispute, the insurer's current grievance page provides the next escalation channel: Manager@libertyinsurance.in.
Forward the original complaint and response rather than starting again. Explain exactly what remains unresolved and identify any evidence or clause Liberty has not addressed.
Step 4: Escalate to the Service Head
If you remain dissatisfied, Liberty's next published escalation email is ServiceHead@libertyinsurance.in.
At this point, your representation should already contain a clean chronology showing the original claim decision, first complaint, Liberty's response, Manager-level escalation and remaining points of disagreement.
This makes it easier for the next grievance level to understand the dispute without treating it as a new generic service request.
Step 5: Grievance Redressal Officer and Chief GRO
Liberty's current grievance page then provides for escalation to its Grievance Redressal Officer, followed by its Chief Grievance Redressal Officer.
The current role-based grievance email published by Liberty is gro@libertyinsurance.in.
Use the official role and Liberty's current grievance page rather than relying on an individual officer's name because personnel can change.
How Long Should a Liberty General Grievance Take?
Liberty publishes several timing indicators, and they should not be treated as one cumulative waiting period.
IRDAI's Bima Bharosa guidance states that an insurance company should resolve a grievance within 15 days of receipt.
Separately, Liberty's June 2026 KMP performance disclosure says the company had redressed grievances with an average turnaround time not exceeding seven days. That is a reported performance average, not necessarily a guaranteed service deadline for every individual grievance.
The Insurance Ombudsman uses a different insurer-first framework and states that the insurer should deal with the complaint within 30 days before the no-response route to the Ombudsman arises.
Liberty General Health Claim Disputes
Liberty operates its health claims through Liberty Health 360. Current claim registration channels include 1800-266-5844 and health360@libertyinsurance.in.
Cashless Claim Timelines
Liberty's current health-claims page states that where complete information has been received, initial cashless authorisation is targeted within one hour and final discharge authorisation is targeted within three hours.
These are cashless authorisation timelines, not guarantees that every requested amount will be approved. The insurer may still assess admissibility, policy limits, exclusions, co-payments and other contractual conditions.
Cashless Rejection Does Not Automatically End the Claim
Liberty's own health guidance states that if cashless authorisation is not received or is denied, the insured may settle the hospital bill and submit the claim for reimbursement.
A cashless denial and final claim repudiation are not necessarily the same thing. Preserve the pre-authorisation request, Liberty or TPA response, hospital records, discharge summary, diagnostic reports, final bill, payment receipts and correspondence with Liberty Health 360.
See Tatkal Claims' Cashless Health Insurance Claim Rejected? How to File a Reimbursement Claim guide for the wider process.
Reimbursement Claim Timeline
Liberty's main current reimbursement process says that once complete documents are received, the claim will be settled within 15 days.
The same page also contains an FAQ stating that after receiving all required documents it takes seven working days to process the claim, followed by three banking days for payment after approval.
These are two formulations appearing on Liberty's own current page. They should not be added together as if the policyholder must automatically wait 15 days plus another ten days.
For an escalation, preserve the actual date on which Liberty received the final necessary document and ask the insurer to explain the applicable TAT in your specific case. Recent Liberty health policy wording also states settlement or rejection within 15 days from receipt of the last necessary document.
Pre-Existing Disease and Non-Disclosure Disputes
Where Liberty rejects a claim on the basis of a pre-existing illness or alleged non-disclosure, obtain the proposal form, declaration made at purchase, past medical records, current admission records, repudiation letter, and policy schedule and wording.
The central question is not simply whether an old medical entry exists. The dispute may turn on what the proposal form asked, what the insured knew, what was disclosed, whether the information was material and how it relates to the current claim.
See Tatkal Claims' Health Insurance Claim Rejected for Pre-Existing Disease guide for the broader framework.
Short Settlement and Health Deductions
For a partly paid claim, demand a line-by-line settlement calculation. Possible areas include non-medical items, co-payment, deductible, room-category restrictions, proportionate deductions, sub-limits, policy exclusions, waiting periods and reasonable-and-customary charges.
Use Tatkal Claims' Health Insurance Claim Short-Settled? How to Check and Challenge Deductions guide when analysing the calculation.
Liberty General Motor Claim Disputes
Liberty's current motor claims page says claims can be registered through its toll-free number or online.
The insurer's website states that it will organise a vehicle survey within 24 hours inside city limits and within 48 hours outside city limits.
Recent Liberty motor Customer Information Sheets separately state surveyor appointment within 24 hours from claim registration, survey report within 15 days from appointment, and settlement or rejection within seven days after receipt of the last document.
These statements appear to describe different stages. Appointment of the surveyor is not necessarily identical to the time at which the physical survey actually occurs. Preserve the actual claim-registration, appointment and inspection timestamps if delay becomes part of the dispute.
Accident Repair Disputes
Liberty identifies documents such as the claim form, registration certificate, driving licence, repair bills or estimates, photographs and police documents where applicable.
If the insurer's survey assessment is below the garage estimate, examine whether all accident-related damage was included, depreciation, excluded components, pre-existing damage, deductibles, consumables, betterment, labour rates, and repair-versus-replacement decisions.
A surveyor's assessment should be analysed item by item rather than challenged only on the final amount.
Total Loss and Constructive Total Loss
When the dispute concerns whether a vehicle should be repaired or treated as a total or constructive total loss, obtain the survey report, insured declared value, repair estimate, salvage valuation, policy wording and relevant add-on wording.
Tatkal Claims' Car Total Loss vs Constructive Total Loss: 75% IDV Rule, Salvage & Claim Settlement guide explains the general framework.
Vehicle Theft Claims
Liberty's current motor claims information identifies theft documents including the claim form, registration certificate, entire set of vehicle keys, FIR, final or no-trace report, subrogation and power-of-attorney documents, indemnity bond, financier NOC where applicable and discharge voucher.
If a theft claim is delayed because Liberty says documentation is incomplete, ask the insurer to identify the precise outstanding requirement in writing.
For the wider process, see Tatkal Claims' Car Stolen? Insurance Claim Process, Documents, FIR, Non-Traceable Certificate & Delayed Intimation guide.
How to Structure a Strong Liberty General Appeal
Start with the policy number, claim number, date of loss or hospitalisation, amount claimed, amount rejected or deducted, and date of Liberty's decision.
Then identify what Liberty decided, the policy clause Liberty relies upon, why you disagree with the contractual, factual, medical or survey conclusion, and exactly what you want Liberty to do.
For example, request reconsideration of repudiation, reversal of a specific deduction, the survey assessment, release of an admitted amount, reconsideration of medical evidence or a reasoned written decision.
Attach the strongest evidence and identify every attachment clearly.
Escalating Through Bima Bharosa
If Liberty's internal grievance process does not resolve the matter, a policyholder can register a grievance through IRDAI's Bima Bharosa portal.
IRDAI states that the policyholder should first approach the insurer's grievance officer, submit the grievance in writing with supporting documents, obtain acknowledgement and allow the insurer the prescribed grievance-resolution period.
A Bima Bharosa grievance should include the actual claim dispute, not merely say that the insurer has been unhelpful. Upload the policy, rejection or settlement letter, earlier grievance, insurer response, supporting medical or motor evidence and calculation of the disputed amount.
See Tatkal Claims' Bima Bharosa vs Insurance Ombudsman guide for the differences between the two routes.
When to Approach the Insurance Ombudsman
The Council for Insurance Ombudsmen says the policyholder should first complain to the insurer.
You may approach the Insurance Ombudsman where you are dissatisfied with the insurer's decision or where the insurer has not responded within 30 days, subject to the other eligibility requirements.
The Council currently states that claim value including relevant expenses must not exceed ₹50 lakh, the complaint normally must be filed within one year of the relevant rejection, decision or expiry of the insurer's response period, and the same subject matter should not already be before or disposed of by another court, consumer forum or arbitrator.
The Ombudsman can consider issues including total or partial repudiation, claim delays, disputes over policy terms and certain policy-servicing grievances.
See Tatkal Claims' Insurance Ombudsman Complaint Process in India guide before filing.
7-Day Action Plan After a Liberty General Claim Rejection
| Day | Action |
|---|---|
| Day 1 | Obtain the repudiation letter, settlement sheet or cashless denial. |
| Day 2 | Identify the precise policy clause and claim reason. |
| Day 3 | Collect medical, survey, repair, theft or other supporting evidence. |
| Day 4 | Prepare a clause-by-clause written representation. |
| Day 5 | Submit it through Liberty's grievance channel and obtain acknowledgement. |
| Day 6 | Organise the complete claim chronology and escalation evidence. |
| Day 7 | Identify any unanswered issue and prepare for Manager, Service Head or GRO escalation. |
A written record is more useful in a later escalation than repeated telephone conversations without documentary proof.
Can Tatkal Claims Help With a Liberty General Claim Dispute?
Tatkal Claims assists policyholders dealing with rejected, delayed and short-settled insurance claims.
Depending on the dispute, this may include reviewing Liberty's rejection or deduction reasoning, analysing relevant policy wording, reviewing supporting documents, identifying gaps in evidence, preparing a structured representation, organising escalation through Liberty's grievance ladder, and preparing the matter for Bima Bharosa or the Insurance Ombudsman.
No claim outcome can be guaranteed. Every case depends on its own policy wording, proposal disclosures, documents, facts and applicable rules.
Frequently Asked Questions
Frequently asked questions
Can I appeal a Liberty General claim rejection?
Yes. You can ask Liberty General to reconsider a rejection through its grievance process. Your appeal should address the actual rejection reason and policy clause with supporting evidence.
What is Liberty General's customer-care email?
Liberty currently publishes care@libertyinsurance.in for customer service and first-stage grievances.
What is Liberty General's grievance escalation hierarchy?
The current published sequence is customer care, Manager escalation, Service Head escalation, Grievance Redressal Officer and Chief Grievance Redressal Officer.
What are Liberty's Manager and Service Head escalation emails?
Liberty currently publishes Manager@libertyinsurance.in and ServiceHead@libertyinsurance.in as successive escalation channels.
What is Liberty General's GRO email?
Current Liberty material publishes gro@libertyinsurance.in as its role-based grievance contact.
Does Liberty have a separate grievance email for senior citizens?
Yes. Current Liberty policy and grievance materials publish seniorcitizen@libertyinsurance.in for senior citizens.
What are Liberty's health cashless timelines?
Liberty's current health claims page states initial authorisation within one hour and final discharge authorisation within three hours after complete information or documents are received.
What is Liberty's health reimbursement timeline?
Liberty's current main reimbursement process states settlement within 15 days of receipt of complete documents. Its page also carries a separate operational FAQ referring to seven working days for processing and three banking days after approval for payment.
What motor claim TATs does Liberty publish?
Recent Liberty motor Customer Information Sheets state surveyor appointment within 24 hours, survey report within 15 days from appointment, and settlement or rejection within seven days after receipt of the last document. Liberty's motor webpage separately states that the survey is organised within 24 hours inside city limits and 48 hours outside city limits.
Can a Liberty General dispute go to the Insurance Ombudsman?
Potentially yes, if the insurer-first and other eligibility conditions are satisfied. The Council currently refers to the 30-day insurer response framework, a ₹50 lakh ceiling and a one-year filing period.
Official Sources
Disclaimer: This article provides general information about insurance claim grievance and escalation processes in India. Policy wording, endorsements, claim facts and applicable rules differ between cases. It is not a guarantee that a rejected, delayed or short-settled claim will be reversed.