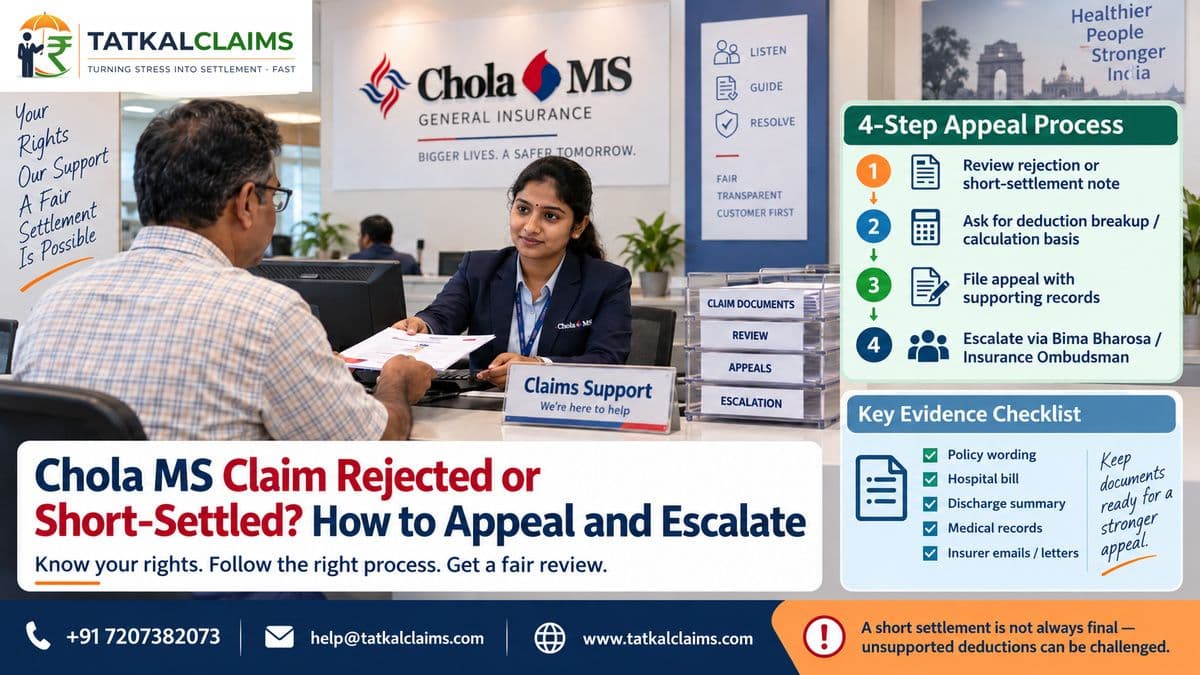
A Chola MS claim rejection, delay or short settlement should be challenged against the exact reason given in writing. A motor own-damage claim, a theft claim, a health cashless request, a reimbursement claim and a partial settlement can involve very different evidence, so the appeal should be built around the specific policy clause, survey finding, medical conclusion, document issue or deduction being relied on.
First: Identify What Happened to Your Chola MS Claim
| Claim problem | What it usually means | Best first move |
|---|---|---|
| Motor own-damage claim rejected | The insurer disputes coverage, causation, documents, vehicle status or survey findings | Get the repudiation reason, survey basis and policy clause in writing |
| Motor claim short-settled | The claim is admitted but repair items, depreciation, excess, salvage or other deductions reduce payment | Ask for the line-by-line settlement calculation |
| Health cashless request denied | Cashless authorisation was refused; reimbursement may still need separate assessment | Preserve the denial reason and complete hospital file |
| Reimbursement claim rejected | A final adverse claim decision has been issued | Challenge the exact medical, policy or document reason |
| Claim delayed | No final decision or payment has been communicated | Create a dated chronology and escalate the delay separately |
If you first need the general framework for repudiation disputes, use our complete insurance claim rejection guide before preparing the Chola MS-specific grievance.
Step 1: Get the Exact Rejection, Deduction or Delay Reason in Writing
Record the policy number, claim number, date of loss or treatment, amount claimed, amount approved, date of decision and the exact reason for rejection or deduction. Ask for the policy clause, survey conclusion, medical basis or document deficiency relied upon if the communication is vague.
Create a short chronology and an indexed evidence set. For motor claims, preserve photographs, FIR where applicable, RC, driving licence, repair estimate, survey communications, invoices and ownership or transfer records. For health claims, preserve the policy wording, proposal disclosures, cashless correspondence, discharge summary, prescriptions, investigations, itemised bills and insurer queries.
Step 2: Register the Complaint With Chola MS Customer Care
Chola MS currently publishes 1800-208-5544 for motor products and 1800-208-9100 for health and other products. Its customer-service email is customercare@cholams.murugappa.com, and its website provides service-request and complaint-registration options.
Do not send only a generic request to reconsider. Quote the claim decision, identify the exact point you dispute, attach the documents that answer it and state the remedy you want. Save the service-request or complaint reference number because Chola’s escalation material asks customers to quote the earlier reference at the next stage.
Step 3: Escalate to the Chola MS Nodal Officer
Recent Chola MS policy information states that if you are dissatisfied with the response or there is a delay beyond the stated internal escalation period, you may escalate to the Nodal Officer at Nodalescalation@cholams.murugappa.com. Quote the previous service-request number and explain which points remain unanswered.
Step 4: Escalate to the Chief Grievance Officer
If the Nodal Officer escalation does not resolve the dispute, Chola MS publishes GRO@cholams.murugappa.com for escalation to the Chief Grievance Officer. IRDAI’s current list of insurer grievance contacts also identifies Chola MS’s grievance-redressal route and the same GRO email address.
How to Challenge Common Chola MS Motor Claim Problems
1. Survey, repair estimate or damage-causation dispute
Compare the survey findings with the accident photographs, repair estimate, workshop diagnosis and the policy wording. Chola’s current private-car own-damage customer information lists an initial survey target of 24 hours from claim intimation, a survey-report target of 15 days from allocation, and approval or rejection within 7 days after receipt of the survey report with the relevant claim documents.
2. Registration, vehicle classification or eligibility dispute
Tatkal Claims already covers a Chola MS electric-cycle claim dispute involving an RTO-registration objection. That judgment is useful as a fact-specific illustration of why the insurer’s stated policy requirement should be compared with the actual vehicle category, registration rules and policy wording. It is not a guarantee of the outcome in another claim.
3. Total loss, constructive total loss or IDV dispute
If the dispute concerns whether the vehicle should be repaired, treated as a total loss, or settled against the insured declared value, use our car total-loss and constructive-total-loss guide to audit the repair-cost, IDV and salvage calculations before escalating.
4. Theft claim, delayed intimation or non-traceable documents
For theft claims, preserve the FIR, police papers, keys, ownership documents, intimation proof and non-traceable or final police report where required. Our car-theft insurance claim guide explains the document sequence and how to address a delayed-intimation objection.
5. Ownership or policy-transfer dispute
If Chola MS raises an ownership, sale or policy-transfer issue, compare the dates of sale, registration transfer, policy endorsement and loss. The stolen-SUV policy-transfer case shows why these dates and the governing policy terms can become central to a motor-claim dispute.
What If the Chola MS Dispute Is a Health Claim?
For a health claim, separate a cashless denial from a final reimbursement repudiation. Ask for the exact medical or policy basis, preserve the hospital file and match each allegation to the policy wording and contemporaneous medical records.
Use the cashless-to-reimbursement guide for a denied cashless request, the PED rejection guide for alleged non-disclosure or waiting-period disputes, and the health short-settlement guide where the claim was admitted but deductions reduced the payout.
Step 5: Escalate an Unresolved Complaint Through Bima Bharosa
If the insurer-level grievance remains unresolved or the response is unsatisfactory, you can register the complaint on IRDAI’s Bima Bharosa portal. IRDAI says the complaint flows to the insurer’s system as well as the IRDAI repository and receives a token number for tracking.
For the difference between regulatory grievance tracking and independent redressal, see Bima Bharosa vs Insurance Ombudsman.
Step 6: Check Whether the Insurance Ombudsman Fits Your Case
The Council for Insurance Ombudsmen says you should first complain to the insurer or insurance broker. If you are dissatisfied with the response, or there is no response within 30 days, an eligible complaint can be filed with the Insurance Ombudsman. Current CIO guidance states that the value of the claim including expenses should not exceed ₹50 lakh and that the complaint should be filed within one year from rejection, repudiation or partial settlement, subject to the applicable procedure.
The same subject matter should not already be pending before or disposed of by another court, consumer forum or arbitrator. Check jurisdiction and eligibility before filing.
If the Ombudsman route fits your case, use our step-by-step Insurance Ombudsman complaint guide for the filing process and document checklist.
A Practical Chola MS Appeal Structure
- Identify the policy, insured person or vehicle, claim number and exact decision you are challenging.
- Quote Chola MS’s rejection reason or disputed deduction exactly as written.
- Explain why the reason is factually, medically, technically or contractually incorrect.
- Attach an indexed set of evidence that directly answers each disputed point.
- State the remedy you want: reconsideration, recalculation, reasoned review, release of pending payment or payment of the disputed admissible amount.
- Preserve every Customer Care, Nodal Officer, GRO, Bima Bharosa and Ombudsman reference for the next stage.
Your 7-Day Action Plan After a Chola MS Claim Rejection
Day 1: collect the policy, claim decision and settlement note. Day 2: build the loss, treatment or repair chronology. Day 3: identify the exact disputed clause, survey conclusion, medical point or deduction. Day 4: collect the missing records or workshop, survey or treating-doctor clarification. Day 5: prepare the written appeal with numbered evidence. Day 6: submit it through the appropriate Chola MS grievance channel and save proof. Day 7: calendar the insurer’s internal escalation point, the 15-day grievance benchmark and any later Ombudsman deadline.
When Tatkal Claims Can Help
If the rejection reason is unclear, the survey or medical evidence is complicated, the settlement calculation does not match the policy, the insurer’s stated reason changes, or repeated grievance attempts do not resolve the dispute, Tatkal Claims can help review the file, identify the disputed issue and structure the next escalation.
No appeal, grievance or claim-resolution service can guarantee payment. The outcome depends on the policy wording, evidence, applicable regulations, limitation periods and the forum that ultimately reviews the dispute.
Frequently asked questions
How do I escalate a Chola MS insurance grievance?
Start with Chola MS Customer Care. Recent Chola materials then provide escalation to the Nodal Officer at Nodalescalation@cholams.murugappa.com and then the Chief Grievance Officer at GRO@cholams.murugappa.com before external redressal where eligible.
What are Chola MS’s main customer-care contacts for claims and grievances?
Chola MS currently publishes 1800-208-5544 for motor products, 1800-208-9100 for health and other products, and customercare@cholams.murugappa.com for customer-service communication.
When can I escalate from Chola MS Customer Care to the Nodal Officer?
Recent Chola customer-information material says you may move through the internal escalation matrix if you are dissatisfied with the response or there is a delay beyond 7 working days. Keep the earlier service-request number and quote it in the escalation.
What if my Chola MS motor claim is rejected because of registration or vehicle-status issues?
Ask for the exact policy clause and factual basis, then compare it with the RC or vehicle category, ownership records, applicable registration requirement and the policy wording. The correct answer depends on the specific vehicle and facts.
Can a Chola MS short-settlement dispute go to the Insurance Ombudsman?
Partial settlement can fall within the Ombudsman complaint framework, subject to the prior-insurer-complaint requirement, current ₹50 lakh monetary limit, one-year filing period and other eligibility conditions.
What should I attach to a Chola MS claim appeal?
Attach the policy, claim decision or settlement note, a short chronology, the exact disputed clause or finding, and an indexed set of supporting records. For motor claims this may include survey, repair, RC, licence and police records; for health claims it may include hospital and medical records.
Sources
Disclaimer: This article is for general informational purposes and does not constitute legal, medical or financial advice. Insurance disputes depend on the exact policy wording, evidence, facts and applicable law.