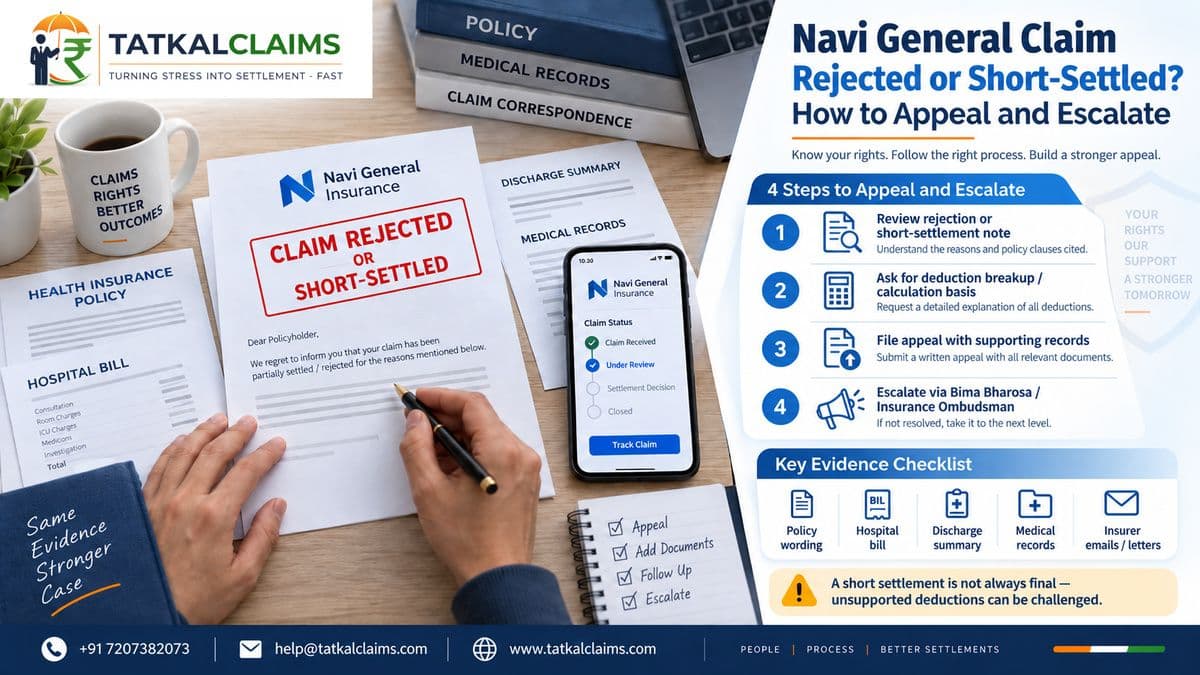
A Navi General claim rejection, delay or short settlement should be challenged against the exact reason given in writing. A health cashless request, reimbursement claim, motor own-damage claim, theft claim and partial settlement can involve very different evidence, so the appeal should be built around the specific policy clause, medical conclusion, survey finding, document issue or deduction being relied on.
First: Identify What Happened to Your Navi General Claim
| Claim problem | What it usually means | Best first move |
|---|---|---|
| Health claim rejected | Navi disputes admissibility because of policy terms, medical evidence, disclosure, waiting period, exclusion or documents | Get the precise medical or policy reason and clause in writing |
| Health cashless request denied | Cashless authorisation was refused; reimbursement may still require separate assessment | Preserve the denial reason and complete hospital file |
| Motor own-damage claim rejected | Coverage, causation, documentation, vehicle status or survey findings are disputed | Obtain the repudiation reason, survey basis and relevant policy clause |
| Claim short-settled | The claim is admitted but deductions reduce the amount payable | Ask for the line-by-line settlement calculation |
| Claim delayed | No final decision or payment has been communicated | Create a dated chronology and escalate the delay separately |
| Claim approved but payment not received | Admissibility may no longer be the dispute; release or transfer of payment is pending | Ask for settlement date, payment reference or UTR and reason for non-credit |
If you first need the broader framework for repudiation disputes, use Tatkal Claims' complete insurance claim rejection guide before preparing the Navi-specific grievance.
Step 1: Get the Exact Rejection, Deduction or Delay Reason in Writing
Record the policy number, claim number, date of treatment or loss, amount claimed, amount approved, date of the decision and the precise reason for rejection or deduction. If Navi's communication is vague, ask it to identify the policy clause, medical conclusion, survey finding or document deficiency being relied upon.
Create a short chronology and an indexed evidence set. For a health claim, preserve the policy wording, proposal-form disclosures, cashless correspondence, discharge summary, prescriptions, diagnostic reports, treating-doctor records, itemised bills, payment receipts and insurer queries. For a motor claim, preserve the policy, RC, driving licence, photographs or videos, FIR or police papers where applicable, repair estimate, garage correspondence, survey communications, invoices, towing records and ownership or policy-transfer documents.
If the dispute is a short settlement, specifically ask Navi for the amount claimed, amount considered, every deduction, the policy basis for each deduction and the final payable amount.
Step 2: Register the Complaint With Navi General
Navi currently publishes +91 74060 12341 as its 24×7 number for claim-related queries. For Navi General Insurance, it also publishes +91 81475 44555 and the toll-free number 1800 123 0004. Its current grievance and turnaround-time document lists insurance.help@navi.com as a customer grievance email.
Do not submit only a generic request saying that the rejection is unfair. Quote Navi's actual decision, identify the point you dispute, explain why the evidence or policy wording does not support that conclusion, attach the documents that answer it and state exactly what you want Navi to do. Save the complaint acknowledgement or reference number because it becomes important at the next escalation level.
Step 3: Escalate to the Manager, Customer Experience
If the initial Navi channel does not resolve the dispute satisfactorily, Navi's current escalation matrix identifies the Manager, Customer Experience. Its current published escalation email is manager.customerexperience@navi.com. At this stage, structure the grievance around the unresolved issue rather than simply forwarding the same complaint again.
Step 4: Escalate to Navi General's Grievance Redressal Officer
If the Manager, Customer Experience does not resolve the dispute, Navi currently identifies Koushik Sangiri as its Grievance Redressal Officer. The current GRO contact is gro@navi.com and +91 81475 44555. Your GRO escalation should contain a concise chronology: when the claim arose, when it was filed, what Navi decided, what evidence you submitted, when the first grievance was made, what response was received and what precise issue remains unresolved.
How to Challenge Common Navi General Health Claim Problems
1. Cashless request denied
A cashless denial should first be separated from a final rejection of the underlying medical claim. If cashless authorisation is refused, preserve Navi's denial communication and the hospital's pre-authorisation documents. If you pay the hospital yourself, retain the original bills, payment receipts, discharge summary, prescriptions and investigation reports. Tatkal Claims' cashless-to-reimbursement guide explains how to approach reimbursement after a cashless denial.
Navi's current health service parameters state that initial cashless approval should be provided immediately and no later than one hour, while discharge approval should be given within three hours of the hospital's discharge request. Those service timelines do not by themselves decide whether a disputed claim is ultimately admissible.
2. Reimbursement claim rejected or delayed
Navi's current service parameters specify 15 days from submission of the claim for reimbursement claim settlement or rejection. If the matter goes beyond the applicable period, distinguish a delay complaint from an admissibility dispute. Keep a dated submission record and use Tatkal Claims' claim-delay guide where repeated document requests or inaction are the main problem.
3. Pre-existing disease, waiting period or non-disclosure
If Navi alleges that a medical condition existed before the policy or was not disclosed, reconstruct the position as it stood when the insurance was purchased. Compare the proposal questions with the information actually known at that time, the disclosures made, pre-policy medical records and the records being relied upon by Navi. Use Tatkal Claims' PED rejection guide for a deeper review of non-disclosure, waiting-period and moratorium disputes.
4. Medical necessity or hospitalisation dispute
If Navi disputes whether hospitalisation or treatment was medically necessary, obtain a clear treating-doctor explanation addressing the clinical facts. That may include the presenting symptoms, diagnosis, investigations, reason for admission, treatment provided and why outpatient management would not have been sufficient where that point is disputed.
5. Claim admitted but deductions reduced the payout
Where Navi has admitted the health claim but paid less than expected, obtain the complete settlement sheet. Match every deduction against the applicable policy wording and hospital bill. Tatkal Claims' health insurance short-settlement guide can be used to audit deductions before escalation.
How to Challenge Common Navi General Motor Claim Problems
1. Survey, repair estimate or damage-causation dispute
Navi's current non-health claim service parameters say a surveyor should be appointed within 24 hours of claim intimation, the survey report should be received within 15 days of appointment, and the claim decision should follow within 7 days from the survey report. Where the dispute concerns whether particular damage arose from the insured accident, compare the survey position with photographs, the accident chronology, workshop diagnosis, repair estimate and policy wording.
2. Motor claim settlement delay
Navi's current non-health service parameters state 15 days from receipt of the last document for settlement of a claim, while third-party claims have a separately stated 30-day timeline. If Navi says documents remain outstanding, ask it to identify each outstanding requirement and maintain a dated submission record.
3. Total loss, constructive total loss or IDV dispute
If the dispute concerns whether the vehicle should be repaired, treated as a total loss or settled according to its insured declared value, check the repair estimate, IDV, applicable policy wording and any salvage calculation. Tatkal Claims' car total-loss and constructive-total-loss guide explains how to examine those calculations before escalating.
4. Theft claim
For a stolen vehicle claim, preserve the FIR, police papers, claim intimation, vehicle documents, available keys and the non-traceable or final police report where applicable. Tatkal Claims' car-theft insurance claim guide provides the broader documentation sequence and explains how delayed intimation can become a disputed issue.
5. Licence, vehicle use, ownership or policy-condition dispute
If Navi relies on a driving-licence issue, vehicle-use condition, ownership mismatch or policy transfer, establish the exact facts and dates. Compare the RC, licence, policy schedule, endorsements, sale or transfer documents and date of loss with the specific clause Navi relies upon. Do not assume that every technical discrepancy automatically defeats the claim; the outcome depends on the policy wording, applicable law and the facts.
Step 5: Escalate an Unresolved Complaint Through Bima Bharosa
If the insurer-level grievance remains unresolved or Navi's response is unsatisfactory, you can register the complaint through IRDAI's Bima Bharosa grievance platform. A complaint registered through Bima Bharosa flows to the insurer's system as well as IRDAI's repository and receives a token number that can be used for tracking.
Bima Bharosa is a regulatory grievance mechanism. It is not the same process as approaching the Insurance Ombudsman. Tatkal Claims' Bima Bharosa vs Insurance Ombudsman guide explains the difference between the two routes.
Step 6: Check Whether the Insurance Ombudsman Fits Your Case
The Council for Insurance Ombudsmen says that you should first complain to the insurer or insurance broker. If you are dissatisfied with the response, or there is no response within 30 days, an eligible complaint can be filed with the Insurance Ombudsman. Current CIO guidance states that the value of the claim including expenses should not exceed ₹50 lakh, and the complaint should generally be filed within one year from rejection, repudiation or partial settlement, subject to the applicable procedure.
You should not already have approached another court, consumer forum or arbitrator on the same subject matter. Check jurisdiction and eligibility before filing.
If this route fits your case, Tatkal Claims' step-by-step Insurance Ombudsman complaint guide explains the filing process and documents.
What If Navi Approved the Claim but the Payment Has Not Reached You?
Do not automatically reopen the entire admissibility dispute if Navi has already approved the claim. Ask for the approved amount, settlement date, payment status, payment reference or UTR where available, bank details used for the transfer and the reason for any failed or pending transaction. Your written grievance should clearly identify the problem as an approved-but-unpaid claim.
A Practical Navi General Appeal Structure
- Identify the policy, insured person or vehicle, claim number and the exact decision being challenged.
- Quote Navi's rejection reason or disputed deduction exactly as written.
- Explain why that conclusion is factually, medically, technically or contractually incorrect.
- Attach an indexed evidence set that directly answers each disputed point.
- State the remedy you want: reconsideration, recalculation, release of pending payment, reasoned review or payment of the disputed admissible amount.
- Preserve every customer-service, Manager Customer Experience, GRO, Bima Bharosa and Ombudsman reference for the next stage.
Your 7-Day Action Plan After a Navi General Claim Rejection
Day 1: collect the policy, claim decision and settlement note. Day 2: build the treatment, loss or repair chronology. Day 3: identify the exact disputed policy clause, medical conclusion, survey finding or deduction. Day 4: obtain any missing medical, hospital, workshop, police or documentary evidence. Day 5: prepare the written appeal with numbered evidence. Day 6: submit it through the appropriate Navi grievance channel and preserve proof. Day 7: calendar Navi's internal grievance timeline, the applicable Bima Bharosa benchmark and any later Ombudsman deadline.
When Tatkal Claims Can Help
If Navi's rejection reason is unclear, the medical or survey evidence is complicated, the settlement calculation does not match the policy, repeated document requests are delaying the claim, the insurer's stated reason changes, or earlier grievance attempts have not resolved the dispute, Tatkal Claims can help review the file, identify the disputed issue and structure the next escalation.
No appeal, grievance or claim-resolution service can guarantee payment. The outcome depends on the exact policy wording, evidence, applicable regulations, limitation periods and the forum reviewing the dispute.
Frequently asked questions
How do I escalate a Navi General insurance grievance?
Start with Navi's customer-support or claim channel. If the issue remains unresolved, Navi's current escalation matrix provides for escalation to the Manager, Customer Experience at manager.customerexperience@navi.com, followed by the Grievance Redressal Officer at gro@navi.com. External routes may then be available where appropriate.
What is Navi General's claim helpline?
Navi currently lists +91 74060 12341 as its 24×7 number for claim-related queries. It also lists +91 81475 44555 for Navi General Insurance and 1800 123 0004 as a toll-free contact.
Who is Navi General's Grievance Redressal Officer?
Navi currently identifies Koushik Sangiri as its Grievance Redressal Officer. The published GRO email is gro@navi.com.
How long does Navi General have to resolve a grievance?
Navi's current grievance material says it aims to issue final resolution within two weeks. Bima Bharosa separately states that an insurance company should resolve a complaint within 15 days of receipt, so keep the actual submission and acknowledgement dates.
How quickly should Navi process a health reimbursement claim?
Navi's current health service-parameter document states that reimbursement claim settlement or rejection should occur within 15 days from submission of the claim.
What are Navi's current cashless health claim timelines?
Navi's current published service parameters state that initial cashless approval should be immediate and not more than one hour, and discharge approval should be within three hours of the hospital's discharge request.
What are Navi General's motor and non-health survey timelines?
Its current service parameters state that a surveyor should be appointed within 24 hours of claim intimation, the survey report should be received within 15 days from appointment, and the claim decision should be made within 7 days from receipt of the survey report.
Can I approach Bima Bharosa if Navi does not resolve my complaint?
Yes. If the insurer-level grievance is unresolved or its response is unsatisfactory, Bima Bharosa provides a regulatory grievance channel through which the complaint can be registered and tracked.
Can a Navi General rejected or short-settled claim go to the Insurance Ombudsman?
Potentially. Current CIO guidance requires the policyholder to complain to the insurer first. Subject to the applicable conditions, an eligible complaint can proceed if the insurer's response is unsatisfactory or there is no response within 30 days. The current monetary ceiling is ₹50 lakh including expenses, with the applicable one-year filing requirement.
What should I attach to a Navi General claim appeal?
Attach the policy, rejection or settlement communication, a short chronology, the precise disputed reason or clause and an indexed set of supporting documents. For health disputes this may include hospital and medical records; for motor disputes it may include survey, repair, RC, driving-licence, photographic and police records.
Sources
Disclaimer: This article is for general informational purposes and does not constitute legal, medical or financial advice. Insurance disputes depend on the exact policy wording, evidence, facts and applicable law.